Valero Energy Corporation (VLO)
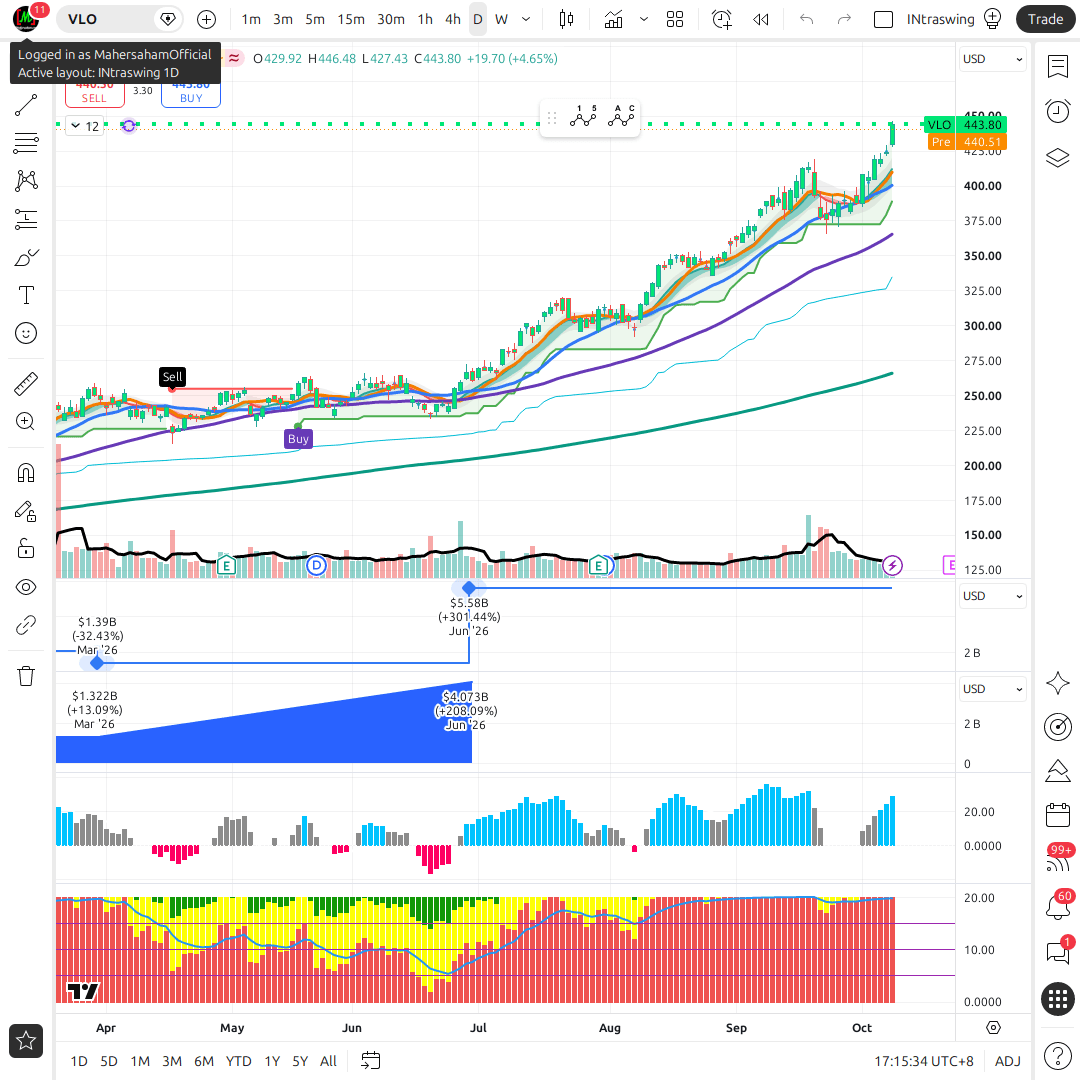
VLO Chart
1D • NYSE
9 Oct, 09:15 am
166.5 KB
Company Profile
What Valero actually does
Valero Energy Corporation (VLO) is one of the largest independent refiners in the world, listed on the NYSE. Its core business is converting crude oil into finished products — gasoline, diesel, jet fuel — and the margin it captures in that process (the 'refining margin' or 'crack spread') is the single biggest driver of earnings. The company runs three segments: Refining (the core segment, roughly 3.2 million bpd of capacity), Renewable Diesel through the Diamond Green Diesel (DGD) joint venture with Darling Ingredients, and Ethanol.
Q1 2026 showed a dramatic turnaround — refining margin jumped to $14.90/bbl, throughput rose 3.6% YoY to 2.9 million bpd, and the Refining segment swung from an operating loss of $530 million (Q1 2025) to operating income of $1.8 billion. Company-wide revenue came in at $32.38 billion (+7% YoY) with EPS of $4.22, beating analyst estimates.
The Port Arthur situation — a real operational overhang
On March 23, 2026, Valero's Port Arthur refinery (380,000 bpd capacity) suffered a fire and explosion at its distillate hydrotreater unit following a process fluid release. No injuries were reported, but the unit sustained what has been described as 'extensive damage.' As of April 2026, the refinery had partially restarted in stages — a smaller crude unit, coker, hydrocrackers and reformer back online, one distillate hydrotreater restored by late April, with the FCC and alkylation units still being brought back. The larger crude unit is ramping up but remains below normal capacity.
The kerosene hydrotreater is expected back online in Q3 2026. But the diesel hydrotreater — the unit that caught fire — still has no confirmed rebuild timeline. That's not a minor detail: Valero's own Q2 2026 guidance cut Gulf Coast throughput to a range of 1.69-1.74 million bpd specifically because of reduced Port Arthur rates. Anyone assessing Valero right now needs to hold two facts at once: the refining margin environment is genuinely strong, and there's a real, unresolved operational overhang sitting on top of it.
DGD and the renewable bet
Diamond Green Diesel is the largest renewable diesel producer in North America and #2 globally, with roughly 1.2 billion gallons/year of capacity across its Norco (Louisiana) and Port Arthur (Texas) plants. Valero is also expanding SAF (sustainable aviation fuel) capacity — a Port Arthur project can convert up to 235 million gallons/year of renewable diesel capacity into SAF, a longer-term growth angle tied to demand for lower-carbon aviation fuel globally.
Shariah Compliance Status
✅ Valero Energy Corporation (VLO) is confirmed SHARIAH COMPLIANT per Zoya US stock screening reference. Its core business (oil refining, diesel, ethanol) does not involve clearly non-compliant activities (conventional interest-based banking, gambling, alcohol), and the company's financial ratios sit within thresholds accepted by international Shariah screens.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
Q2 2026 (ended 30 Jun 2026): revenue of $44.48 billion (estimate $37.95 billion), net income of $3.7 billion or $12.62 per share (Q2 2025: $714 million, $2.28).
| Quarter | Revenue ($ bn) | EPS ($) | Refining Operating Income ($ bn) |
|---|---|---|---|
| Q2 2026 | 44.48 | 12.62 / 12.54 (adjusted) | 4.5 |
| Q1 2026 | 32.38 | 4.22 | 1.8 |
| Q2 2025 | - | 2.28 | 1.3 |
Segments
- Refining: operating income $4.5 billion, throughput 3.0 million bpd, margin $23.62/bbl
- Renewable Diesel: $717 million (recovered from a weak year-ago quarter)
- Ethanol: $318 million
Balance sheet
Cash of $7.9 billion, debt of $9.1 billion (plus $2.2 billion of finance lease obligations), debt-to-capitalization of 11%. Operating cash flow was $5.6 billion ($4.5 billion adjusted). Shareholder returns were $2.6 billion, 59% of adjusted operating cash flow, above the company's 40-50% target. Q2 capex was $350 million; 2026 capex is guided at about $2 billion.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends
On 16 July 2026 Valero declared a cash dividend of $1.20 per share ($4.80 annualized). At about $413, the yield is roughly 1.16%, down from 1.97% in the previous study purely because the share price rose about 36%.
Q2 shareholder returns totaled $2.6 billion (59% of adjusted operating cash flow). The dividend is a small part; most is buybacks. VLO is better seen as a capital-return story through buybacks than a yield story. If passive income is your priority, this yield is not high.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Energy sector