Chevron Corp. (CVX)
CVX Chart
1D • NYSE
19 Jul, 11:03 pm
192.1 KB
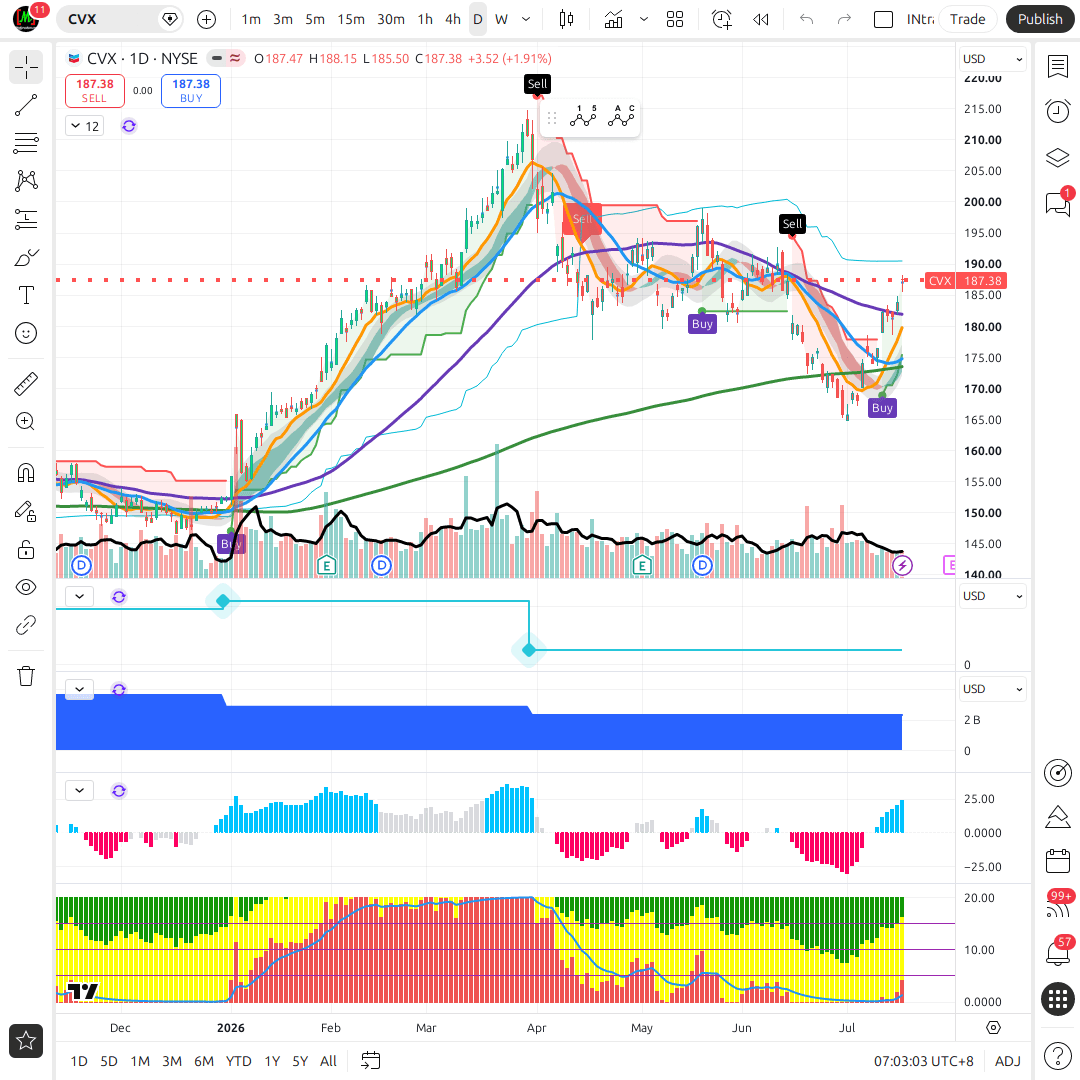
Company Profile: Chevron Corp. (CVX)
From Legacy Major to Guyana Owner
Chevron's story in 2026 is no longer just 'a stable American oil major.' After years of arbitration dispute with ExxonMobil over the right-of-first-refusal on Guyana's Stabroek Block, Chevron finally won that arbitration in mid-2025 and completed its roughly $53 billion all-stock acquisition of Hess Corporation the same year. This was not a marginal bolt-on — it was a structural re-rating event that removed an 'uncertainty discount' that had suppressed CVX shares for roughly 18 months during the arbitration standoff.
As a result of this acquisition, Chevron now holds a 30% non-operated stake in the Stabroek Block — one of the largest oil discoveries in the last decade, with 11 billion-plus barrels of oil equivalent (boe) in recoverable resources, operated by ExxonMobil. Q1 2026 was the first full quarter with Hess contribution, and the results were clear: net oil-equivalent production rose 24% year-over-year, with Hess alone contributing +595 thousand barrels of oil equivalent per day (MBOED) — Guyana +290 MBOED, Bakken +185 MBOED, and Gulf of America +120 MBOED. Organic Permian growth added another +75 MBOED.
The narrative is simple but important: Chevron is no longer just a legacy Permian/international major — it bought its way into one of the best conventional oil growth assets in the world (Guyana), while simultaneously restructuring for cost efficiency.
Q1 2026 Segment Breakdown
| Segment | Revenue/Performance | YoY Trend |
|---|---|---|
| US Upstream | $2,112 million | +$254 million — higher sales volumes despite higher D&A and opex from Hess asset step-up |
| International Upstream | ~$1.8 billion | Slightly down — timing effects, higher D&A, FX impact |
| US Downstream | $196 million | Up from $103 million — record refining throughput above 1 million barrels per day in March |
| International Downstream | Loss of ~$1.0 billion | Lower margins, higher costs, timing effects — a real structural drag, not a one-off |
It's worth being honest here: the International Downstream segment is a genuine weak spot on Chevron's balance sheet right now. Upstream volume growth is real and Hess-driven, but international downstream is a recurring cash drain, not just a one-time surprise.
Shariah Compliance Status
Per Zoya's screening methodology, Chevron (CVX) is classified as SHARIAH COMPLIANT. Integrated oil and gas majors like Chevron generally pass Shariah business-activity screens, and the company's debt-to-equity ratio (~24%) sits well below the interest-bearing debt threshold (~30-33%) commonly used in Shariah screening. This status reflects Zoya's determination, not this platform's own assessment — investors are encouraged to verify independently before making decisions.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation: Chevron Corp. (CVX)
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison: CVX vs XOM, COP, Shell, BP, TotalEnergies
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags: The Real Risks Behind Chevron's Growth Story
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessChevron Scorecard: Evaluating 8 Key Criteria
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts: What to Watch Next
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion: Scale Play or Value Trap in Disguise?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Energy sector