Simon Property Group, Inc. (SPG)
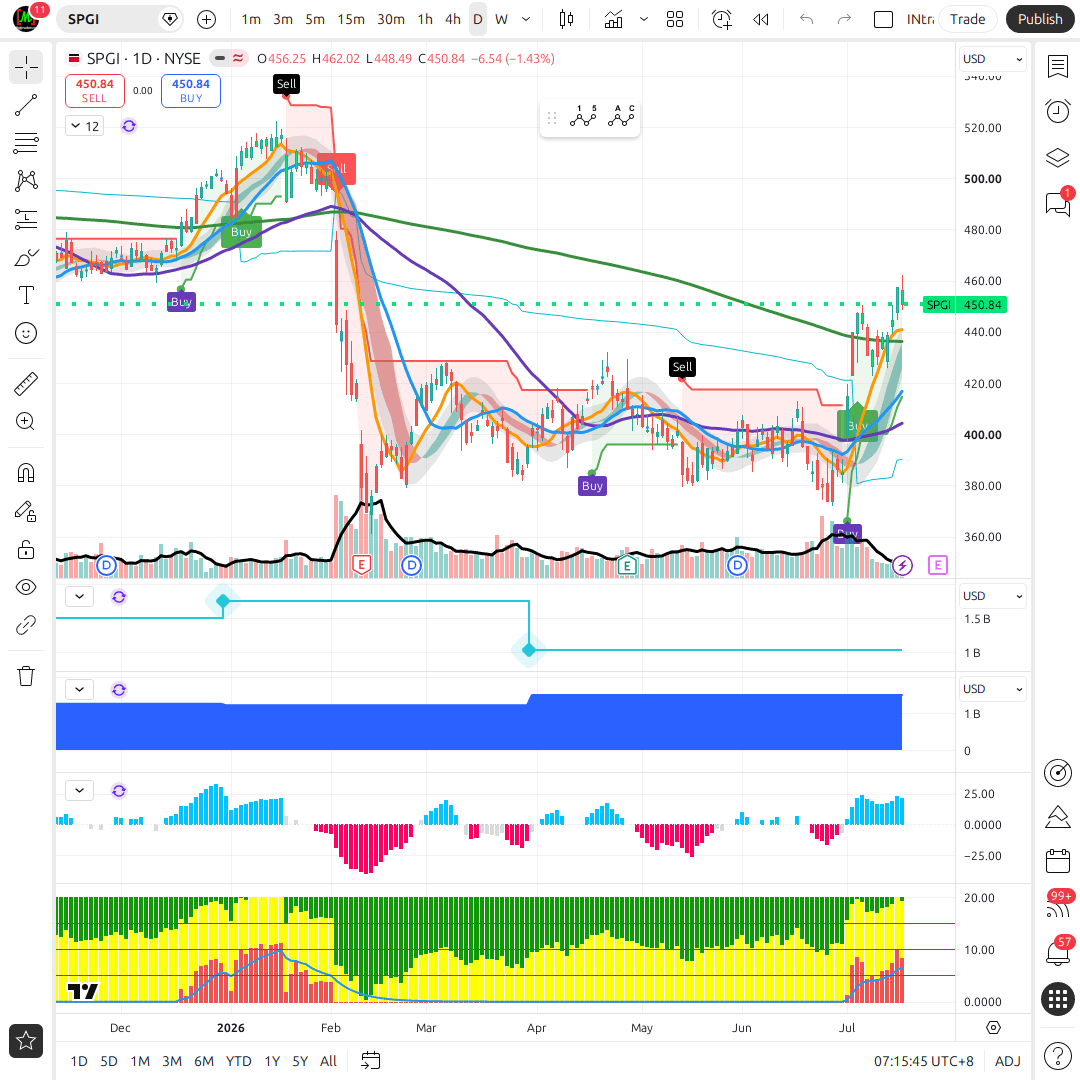
SPG Chart
1D • NYSE
19 Jul, 11:15 pm
181.6 KB
Company Profile
Simon Property Group: The King of Premium North American Malls
Simon Property Group (SPG) is the largest owner and operator of premier shopping, dining, entertainment and mixed-use destinations in North America — a portfolio that also includes international luxury malls following the 2020 acquisition of Taubman Realty Group. This isn't a generic mall company — SPG owns the top tier of the industry: the best-located malls, premium tenant mix (Chanel, Louis Vuitton through Apple, Zara), and the highest foot traffic.
The "malls are dying" narrative that dominated 2015–2021 (peak e-commerce disruption, mass closures of B/C-grade malls) has simply not played out for SPG's top-tier "A"-quality portfolio. The latest data (Q1 2026) tells the opposite story:
- Occupancy 96.0% as of March 31, 2026 (up from 95.9% a year earlier) — SPG's malls are close to fully leased.
- Base minimum rent per square foot up +5.2% YoY to $61.99 — SPG can command higher rents because demand remains firm.
- TTM retailer sales per square foot up +11.8% YoY to $819 — SPG's tenants are selling more per square foot, a sign of genuinely healthy tenant businesses.
All three metrics are moving in the same direction at once — occupancy up, rent up, tenant sales up. That combination is rare and shows SPG's premium malls remain the preferred destination for the world's best retailers, even in the e-commerce era.
Strategic Pivot: From Mall Landlord to Mixed-Use Operator
SPG's core strategy now centers on converting vacant anchor boxes (former Sears, former department stores that shuttered) into mixed-use development — apartments, hotels, entertainment, and dining. Why does this matter? New mall construction in the US is at a historic low — there's effectively no new competitive supply coming online. So SPG is maximizing the value of the premium land it already owns.
Concrete 2026 projects include:
- Boca Raton Town Center — replacing a shuttered Sears with a 197-room hotel, a 374-unit apartment tower, and roughly 157,000 sq ft of retail, on approximately 32 acres.
- Redevelopment projects in Nashville, Denver, and Tampa — part of a $250M+ investment program closely tied to the 2025 Taubman Realty Group integration.
Over the past decade, SPG has added more than 3,000 hotel and residential units to its portfolio, with roughly 1,600 more expected to open between 2026 and 2028. The near-term development pipeline is around $2 billion (with more than $1 billion under active construction), and management has also referenced up to $3 billion in further redevelopment opportunity. In short — SPG is no longer just "a mall REIT"; it's increasingly a mixed-use real estate operator/developer monetizing its best-in-class locations well beyond pure retail.
The 2026 Leadership Transition: From David Simon to Eli Simon
This is the single biggest development at SPG this year. David Simon — Chairman & CEO since 1995, one of the youngest Fortune 500 CEOs ever appointed, and the executive who delivered more than 4,500% cumulative total shareholder return since SPG's IPO — passed away in 2026.
His son, Eli Simon, has now been appointed the company's new CEO, continuing what is described as his father's "tested playbook." This is a major governance/succession event — normally a red flag for founder-led companies — but SPG's board had reportedly been running succession planning for some time, and the market has so far not meaningfully punished the stock (shares remain near all-time highs).
As an indicator of family-shareholder alignment, David Simon held approximately 953,924 shares (~$212M in value) as of 2026 — a large insider stake that forms important context carried into the Eli Simon era.
Shariah Compliance Status
SPG is classified as NON-COMPLIANT with Shariah principles. As a US Real Estate Investment Trust (REIT), SPG's capital structure relies heavily on interest-based debt — including the new $5.0 billion revolving credit facility closed in March 2026. This conflicts with Islamic finance principles that prohibit riba (interest). Investors prioritizing Shariah-compliant portfolios are advised to avoid this stock or seek a certified Shariah-compliant real estate alternative.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Property sector