TONG HERR RESOURCES BHD (TONGHER)
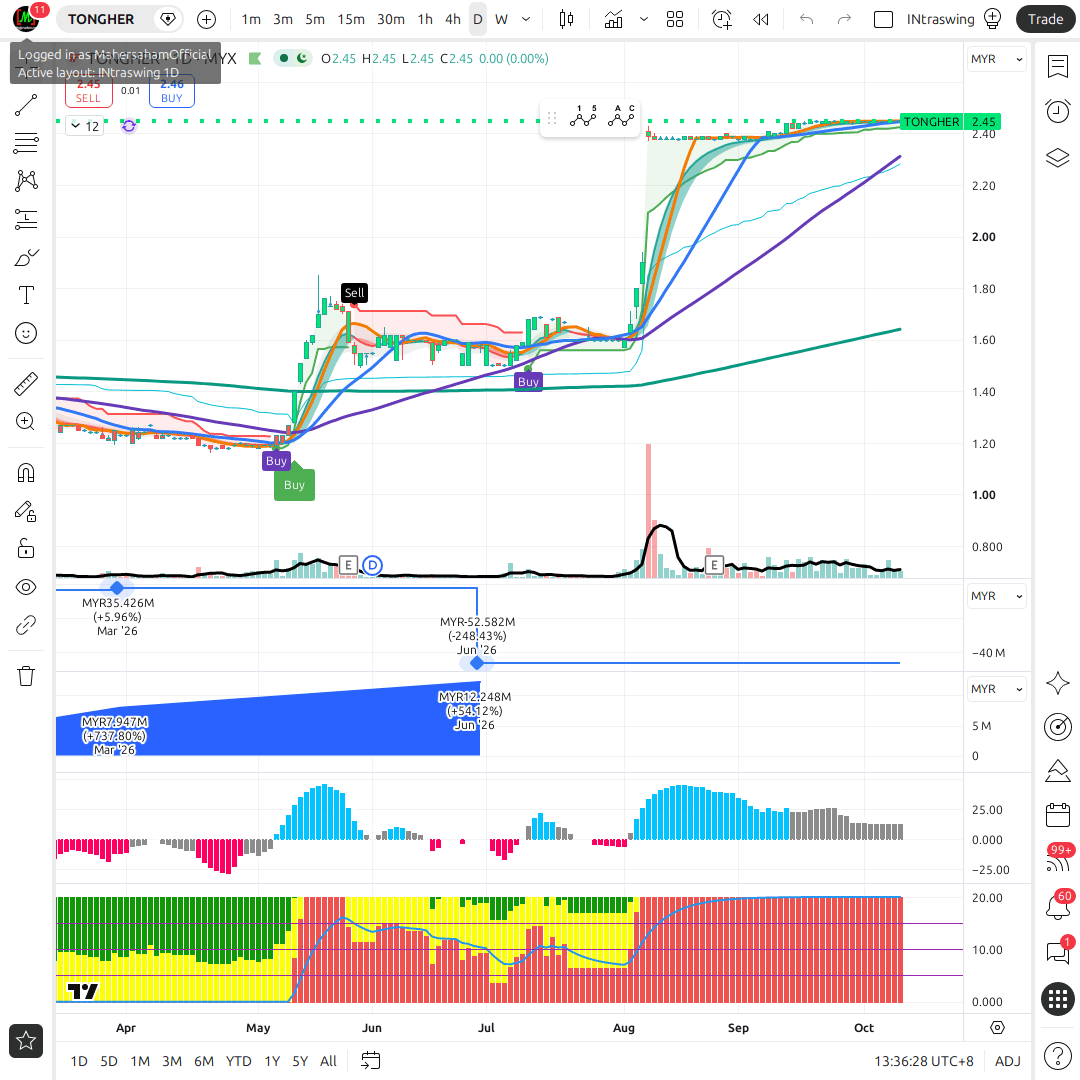
TONGHER Chart
1D • MYX
9 Oct, 05:36 am
166.4 KB
Company Profile - Tong Herr Resources Bhd
Company Profile: Tong Herr Resources Bhd (TONGHER, 5010)
Imagine a Malaysian manufacturer that has been exporting precision hardware to Europe and the US for decades, holds nearly RM92 million in net cash, carries net tangible assets of RM3.53 per share - yet trades at just RM1.46. This is not a distressed business. This is Tong Herr Resources Bhd, a stainless steel fastener maker that has quietly become one of the most compelling deep-value situations on Bursa Malaysia.
Who is Tong Herr?
Tong Herr Resources Bhd is a Malaysia-based investment holding company listed on Bursa Malaysia under stock code 5010 (TONGHER) in the Metals sector. The company operates through two principal segments:
- Segment 1 - Stainless Steel Fasteners: This is the CORE business. The company manufactures nuts, bolts, screws, and all other threaded items in stainless steel. Manufacturing operations are conducted at two locations - the main plant in Perai, Penang, Malaysia and a second plant in Thailand. This dual-country manufacturing footprint provides production risk diversification.
- Segment 2 - Aluminium Extrusion Products: A supporting segment producing aluminium extrusion products and related items. Smaller than the fastener segment but contributes revenue diversification.
Business Model: Export-Heavy, Premium Quality
What distinguishes Tong Herr from ordinary metals companies is its extraordinary export profile. More than 70% of the company's revenue comes from exports, with key markets including:
- 🇩🇪 Europe (Germany, Italy, Netherlands) - largest market, representing approximately 40%+ of revenue
- 🇺🇸 United States - approximately 15%+ of revenue
- 🇯🇵 Japan - premium market with high quality requirements
- 🌏 Rest of Asia - including regional markets
This export orientation means Tong Herr is not a domestic market player dependent on Malaysian demand. They compete globally with customers who demand consistently high quality.
Scale of Operations
The company employs approximately 775 people and has 153.52 million shares outstanding. This is a mid-sized company with a solid operational footprint across two countries.
Shariah Compliance Status
✅ Tong Herr Resources is classified as a Shariah-compliant security on the Securities Commission Malaysia (SC) List of Shariah-Compliant Securities (updated 29 May 2026). It is therefore accessible to investors who require Shariah-compliant exposure. (An earlier version wrongly labelled this non-compliant due to a data error.)
Recent Corporate Actions
June 2025 - Taiwan Asset Disposal (Positive Signal): Subsidiary Tong Herr Aluminium Industries Sdn Bhd disposed of its shareholding in Han Tec Precision Industry Co., Ltd. in Taiwan. This is a positive signal - management is pruning legacy positions and refocusing capital on core operations. Asset disposals of this nature indicate disciplined capital allocation.
January 2024 - Founding Shareholder Restructuring: Co-founder Tsai Ching-Tung ceased to be a substantial shareholder through Allrich Corp following an investment entity restructuring. Important context: this was a corporate holding structure reorganisation, not a distress sale or vote of no confidence. The founding Tsai family retains control through other entities, and management continuity was maintained.
Why This Stock Commands Attention
📈 NTA of RM3.53 vs price of RM1.46 = a 59% discount to book value. You are effectively buying a functioning manufacturing business at 41 cents for every ringgit of assets. Add RM92 million in net cash (approximately 57 sen cash per share), and Tong Herr offers a margin of safety rarely found on Bursa Malaysia.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
Important note: the previous write-up (June 2026 update) mistakenly displayed another company's (DAYANG Enterprise) financial table in this section due to an internal database mix-up. The table below is TONGHER's ACTUAL figures, re-verified against official quarterly filings.
| Quarter | Revenue (RM m) | Net Profit to Shareholders (RM m) | EPS (sen) | DPS (sen) |
|---|---|---|---|---|
| Q2 FY2026 (Jun 2026) | 125.71 | 8.22 | 5.35 | 0.00 |
| Q1 FY2026 (Mar 2026) | 120.47 | 4.81 | 3.13 | 3.30 |
| Q4 FY2025 (Dec 2025) | 120.58 | -1.29 | -0.84 | 0.00 |
| Q3 FY2025 (Sep 2025) | 141.69 | 0.32 | 0.21 | 0.00 |
| Q2 FY2025 (Jun 2025) | 144.75 | 0.72 | 0.47 | 0.00 |
| Q1 FY2025 (Mar 2025) | 153.75 | 6.01 | 3.91 | 3.30 |
H1 FY2026 (Jan-Jun 2026): revenue of RM246.18 million (down 17.5% YoY from RM298.50 million in H1 FY2025), but net profit to shareholders of RM13.03 million - up ~94% YoY from RM6.73 million in H1 FY2025. This means margins improved materially even as sales were lower, reversing the weak Q3-Q4 FY2025 trend (which included a Q4 loss).
Balance sheet: Net cash of ~RM95.27 million (~62 sen/share), price-to-book (P/B) at the current price of RM2.41 is ~0.68x (NTA estimated at ~RM3.53/share). Market cap is now ~RM369.98 million versus ~RM224-238 million before the privatisation announcement.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends
Correction note: the Dividends section in the previous write-up (June 2026) mistakenly showed another company's figures (a 7 sen dividend, 9.21% yield) - that was NOT TONGHER's data. TONGHER's actual dividend history is more modest and consistent: the company typically declares one dividend (interim/final) of around 3.30 sen per share a year, usually alongside Q1 results (e.g. 3.30 sen was declared with both Q1 FY2025 and Q1 FY2026 results). No dividend was declared for Q2, Q3 or Q4 FY2025, and none was declared alongside Q2 FY2026. The trailing 12-month dividend yield is now about 1.39% at the current price of RM2.41 - much lower than the 2%+ level seen at RM1.46-1.51 previously, purely because the share price has jumped on the privatisation proposal, not because of any change in dividend policy.
Most important point for shareholders right now: if the proposed Selective Capital Reduction (SCR) at RM2.55/share is approved, it will entirely replace any future dividend consideration for entitled shareholders - you would instead receive a one-off RM2.55 cash payment per share and the shares would be cancelled/delisted, rather than continuing to receive periodic dividends.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation - Tong Herr Resources Bhd
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Metals & Mining sector