Starbucks Corp. (SBUX)
SBUX Chart
1D • NASDAQ
15 Sept, 12:04 am
181.4 KB
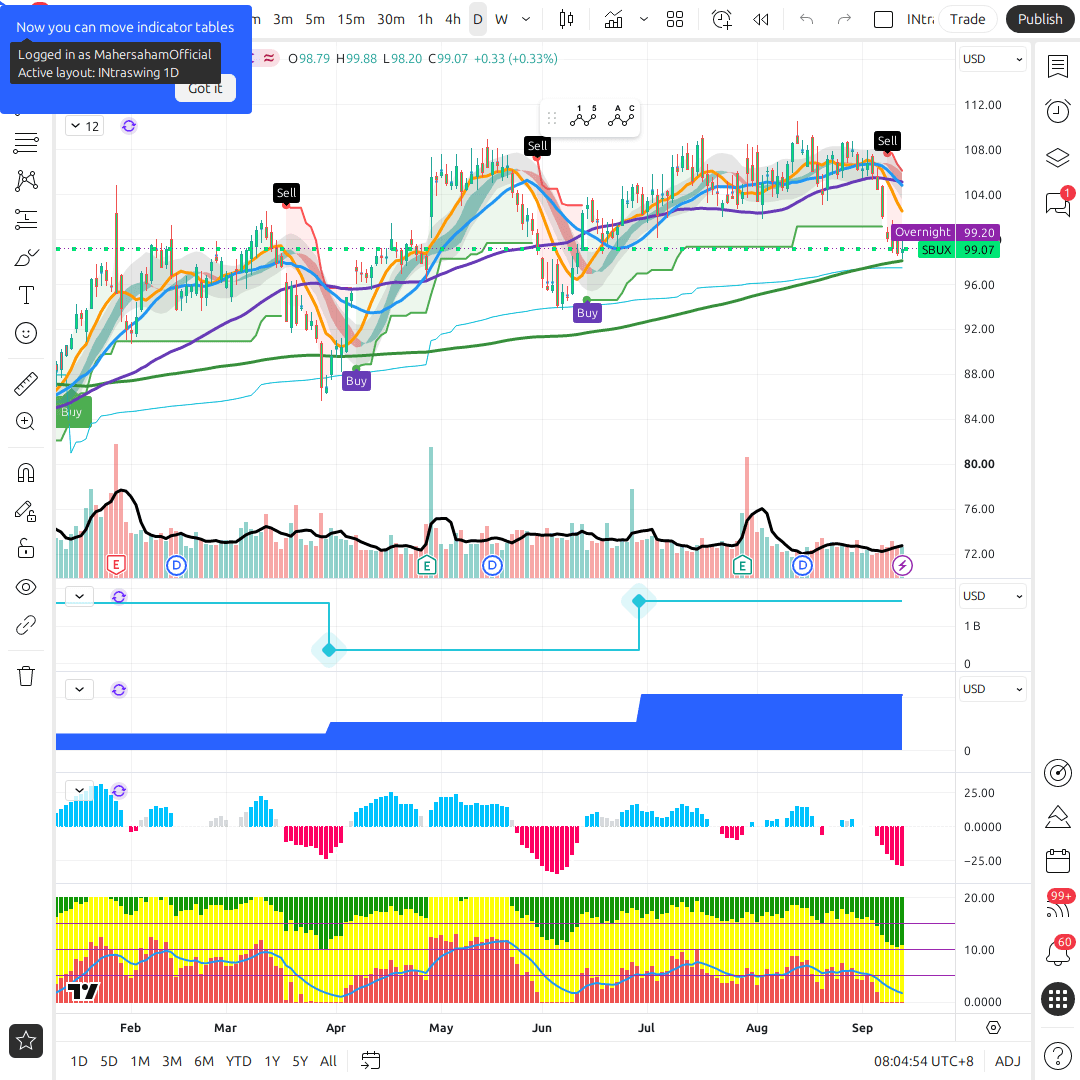
Company Profile: Starbucks Corp. (NASDAQ: SBUX) - The 'Back to Starbucks' Transformation Narrative
Starbucks isn't just 'the world's biggest coffee chain' anymore - the SBUX story today is a turnaround story. Since Brian Niccol (former Chipotle CEO) took over as Chairman and CEO in September 2024, Starbucks has been running its 'Back to Starbucks' agenda: simplify the menu, cut order-to-serve time (targeting under 4 minutes per drink), de-emphasize over-reliance on mobile ordering, and refocus on the 'third place' experience - a place customers come to sit and connect, not just grab-and-go.
At its Investor Day on 29 January 2026, the company declared 'Starbucks is back'. But the real proof point came in Q2 FY2026 (quarter ended 29 March 2026) - for the first time in over two years, revenue AND EPS grew simultaneously in the same quarter. Revenue hit $9.5 billion (+9% YoY), non-GAAP EPS reached $0.50 (+22% YoY). Press coverage framed this as 'the turn in the turnaround'.
Segment Breakdown
Starbucks operates two main reporting segments:
- North America - the largest segment by revenue, with comparable store sales up +7.1% in Q2 FY2026 (transactions +4.4%, average ticket +2.6%). This segment is the biggest beneficiary of 'Back to Starbucks' so far.
- International - comps up +2.6% (transactions +2.1%, ticket +0.5%), slower than North America. Within this segment, China remains the toughest challenge - China comps were only +0.5%, and ticket actually declined -1.6% (meaning growth came from discounting, not pricing power).
So while International segment margin looks impressive at 19.4% (+780bps YoY), a meaningful chunk of that jump is attributable to restructuring/gain items tied to the China JV transaction, not pure operational strength - an important nuance for investors to understand before getting too excited about the International margin figure alone.
Management Team (A Fully New C-Suite)
- Brian Niccol - Chairman & CEO since Sept 2024, former Chipotle CEO. He personally drives the entire 'Back to Starbucks' strategy.
- Cathy R. Smith - CFO since March 2025, former CFO/Treasurer at Nordstrom, with prior CFO roles at Target, Express Scripts, Walmart International, and GameStop.
- Mike Grams - COO since June 2025, overseeing global coffeehouse development and global supply chain.
Shariah Compliance Status
Per the US Shariah-compliant stock reference (zoya_us_stock_reference), SBUX is classified as Shariah COMPLIANT. This means the company's core business (coffee/food sales) and financial ratios currently pass standard Shariah screening - but this status can change over time, so Shariah-conscious investors should re-check periodically, especially given the negative shareholders' equity structure discussed in the Financials section.
Key Corporate Actions
- Sale of a 60% China JV stake to Boyu Capital - closed 30 March 2026, valuing the China business at an enterprise value of $4 billion. Starbucks retains 40% ownership plus brand/IP licensing rights.
- $1 billion restructuring plan - announced Sept 2025, comprising roughly $150 million in employee separation costs and ~$850 million in store-closure-related charges.
- ~500 planned store closures in North America; the company says it returns to expansion mode in FY2026.
Note: SBUX is listed on NASDAQ (United States) and trades in USD - it is not a Bursa Malaysia (KLSE) stock. Malaysian investors need an international brokerage account to trade this counter.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
Q3 FY2026 (quarter ended 28 Jun 2026)
| Metric | Result |
|---|---|
| Revenue | $9.3B, down 1% y/y |
| GAAP EPS / non-GAAP EPS | $0.91 / $0.85 |
| Global comparable sales | +7.9% |
| North America comparable sales | +8.1% (transactions +4.5%, ticket +3.5%) |
| Non-GAAP operating margin | 14.4%, up 430 bp |
| FY26 adjusted EPS guidance | $2.55-$2.65 (from $2.25-$2.45) |
Revenue is flat to down while profit rebounds: margin repair, not top-line growth, is doing the work.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends
Regular dividend
Starbucks pays a regular quarterly dividend. Yield is moderate, not the main reason to own it.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Consumer Discretionary sector