Ichor Holdings, Ltd. (ICHR)
ICHR Chart
1D • NASDAQ
10 Jul, 11:30 pm
171.9 KB
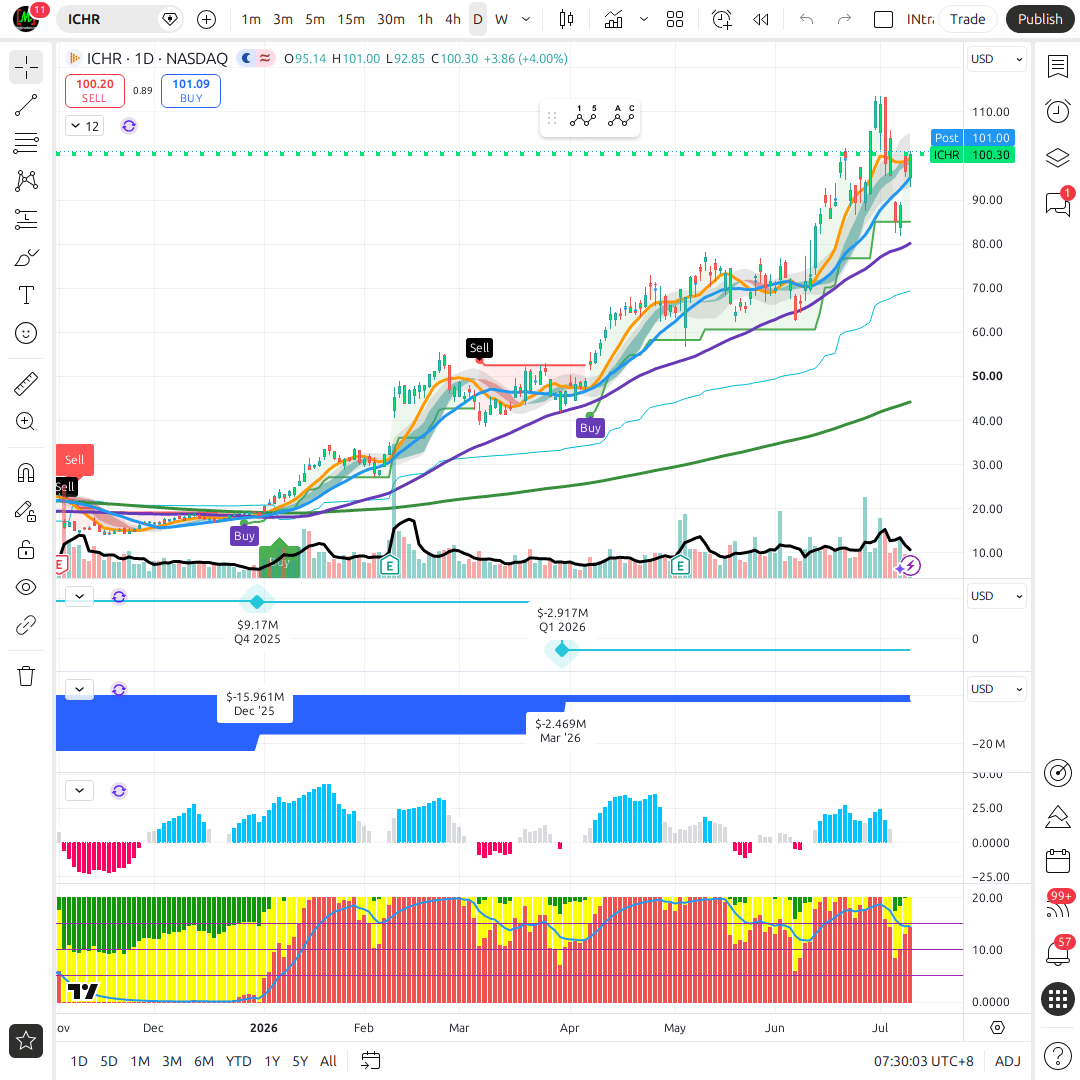
Company Profile: Ichor Holdings (ICHR)
The Real Ichor Story: More Than Just a 'Semiconductor Company'
When you hear 'semiconductor equipment', you probably picture chipmakers like Nvidia or TSMC. Ichor Holdings (ICHR) is different — it is a critical supplier of fluid- and gas-delivery subsystems to the giant wafer fab equipment (WFE) OEMs: Lam Research, Applied Materials, and ASML. In plain terms, Ichor builds the precision 'plumbing' that delivers specialty gases and reactive chemicals into the machines that manufacture semiconductor chips.
Two core product lines: gas delivery subsystems (deliver, monitor, and control specialty gases for etch and deposition tools) and chemical delivery systems (blend and dispense reactive liquid chemistries for CMP, electroplating, and cleaning). These are not commodity parts — a small error in gas or chemical delivery can ruin an entire wafer batch worth millions of dollars. That is why major OEMs like Lam and AMAT rely on Ichor as a long-term, deeply integrated partner.
The Turnaround Story: From Trough to Recovery
This is the single most important thing to understand before looking at any other number in this report. Ichor is emerging from a painful WFE down-cycle — FY2025 marked the trough, with net losses widening. Since then, the company has delivered two consecutive quarters of sequential improvement in revenue, margin, and EPS, and management has guided for the next quarter to continue the same trend. This is not a 'new product' or 'new market' story — it is a classic cyclical recovery in semiconductor capital equipment, driven by an AI-fueled WFE capex upcycle.
A Global Manufacturing Footprint
Ichor operates manufacturing facilities in the United States, Singapore, Malaysia, and Mexico. This footprint is not incidental — it is specifically designed to support just-in-time delivery to OEM customers, who typically need components delivered precisely when and where their own systems are being assembled. The Malaysia presence is worth noting for local readers — while Ichor itself trades on NASDAQ (not Bursa Malaysia), its manufacturing operations do have a footprint in our region.
Structural Risk: 76% Customer Concentration
This is a fact you must understand before considering this stock: Lam Research and Applied Materials combined accounted for 76% of Ichor's FY2025 revenue. ASML is also a top customer. This is not a minor risk to gloss over — it means Ichor's fortunes are tightly bound to the capex decisions of essentially two or three companies. If Lam or AMAT cut orders (for example, because their own chipmaker customers delay investment), the impact hits Ichor more sharply and directly than it would a more diversified supplier.
Shariah Compliance Status
Ichor Holdings, Ltd. (ICHR) is verified as SHARIAH COMPLIANT in our reference database. This means its core business activity — manufacturing semiconductor equipment components — does not involve prohibited/non-compliant activities. That said, you are still encouraged to independently verify the financial ratios (debt levels, interest-bearing cash) against your preferred Shariah screening standard before making an investment decision.
The $200 Million Capital Raise — Why It Matters
In Q2 FY2026, Ichor completed a $200 million at-the-market (ATM) equity offering. In plain terms — the company sold new shares directly into the market to raise cash, rather than taking on debt. Yes, this is dilutive (existing shareholders' ownership stake is slightly reduced), but strategically it puts Ichor's balance sheet in a stronger position heading into the emerging WFE upcycle — more cash on hand means more flexibility to fund working capital (which runs high in a capital-intensive manufacturing business like this) without leaning further on debt.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis: Ichor Holdings (ICHR)
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis: Ichor Holdings (ICHR)
Revenue and Profit Trend: From Trough to Recovery
The table below shows Ichor's revenue and earnings trajectory across recent fiscal years and the latest quarters — this is the single most important story for understanding the company's current financial performance.
| Period | Revenue | Net Income / EPS |
|---|---|---|
| FY2023 | $811.1M | — |
| FY2024 | $849.0M | Net loss (deepened into FY2025) |
| FY2025 | $947.65M (+11.6% YoY) | Net loss -$52.78M |
| Q4 FY2025 | $223.6M | Diluted EPS -$0.46 |
| Q1 FY2026 | $256.1M | Net loss -$2.5M, diluted EPS -$0.07 |
| Q2 FY2026 | $294.8M (+15% QoQ, +24% YoY) | Net income +$1.0M; GAAP EPS $0.03, non-GAAP EPS $0.34 |
| Q3 FY2026 guidance | $315-345M (midpoint +12% QoQ) | Non-GAAP EPS guidance $0.40-0.50 |
The pattern is clear: revenue grew steadily from FY2023 onward, but profitability lagged well behind — the company posted deepening losses through FY2024-FY2025 even as revenue rose. This is a classic sign of negative operating leverage during a down-cycle — fixed manufacturing costs could not be sufficiently absorbed as volumes fell. Starting in Q1 FY2026, the trend reversed — each quarter has shown sequential improvement in revenue, margin, and EPS, and management's Q3 FY2026 guidance points to a continuation of this trend.
Balance Sheet Snapshot
Cash: $256M (after the $200M ATM capital raise) | Total debt: $123.5M | Equity: $676.2M | Debt-to-Equity ratio: ~18.3% — a moderate, not excessive, level.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends: Ichor Holdings (ICHR)
No Dividend — And Here Is Why
Ichor Holdings has NEVER paid a dividend to shareholders. Over the past five years, total dividends distributed have been $0.00. If you are looking at this stock for passive income, ICHR is not a suitable candidate at this stage.
Why? Two main reasons. First, Ichor is a growth/cyclical company operating in a capital-intensive manufacturing business — cash generated (when there is profit) is better deployed to expand manufacturing capacity, fund working capital (inventory and receivables run high in this business), and support growth through the current WFE upcycle, rather than being distributed as a dividend. Second, and more fundamentally — the company is still loss-making on a trailing annual basis (FY2025 net loss of -$52.78M, TTM EPS still -$1.48). You cannot pay a dividend out of earnings that do not yet exist.
Simple conclusion: at its current point in the cycle, ICHR is NOT a dividend stock. If your investment strategy is focused on yield/income, this stock is not relevant for that purpose at this time.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation: Ichor Holdings (ICHR)
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison — ICHR vs UCTT, MKSI, ENTG, COHU
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags — What You Need to Know Before Buying
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessICHR Scorecard — 8 Criteria
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts — Positive and Negative Across Time Horizons
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion — Momentum Turnaround or Priced-to-Perfection?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold Access