ORKIM BERHAD (ORKIM)
ORKIM Chart
1D • MYX
22 May, 12:52 am
137.6 KB
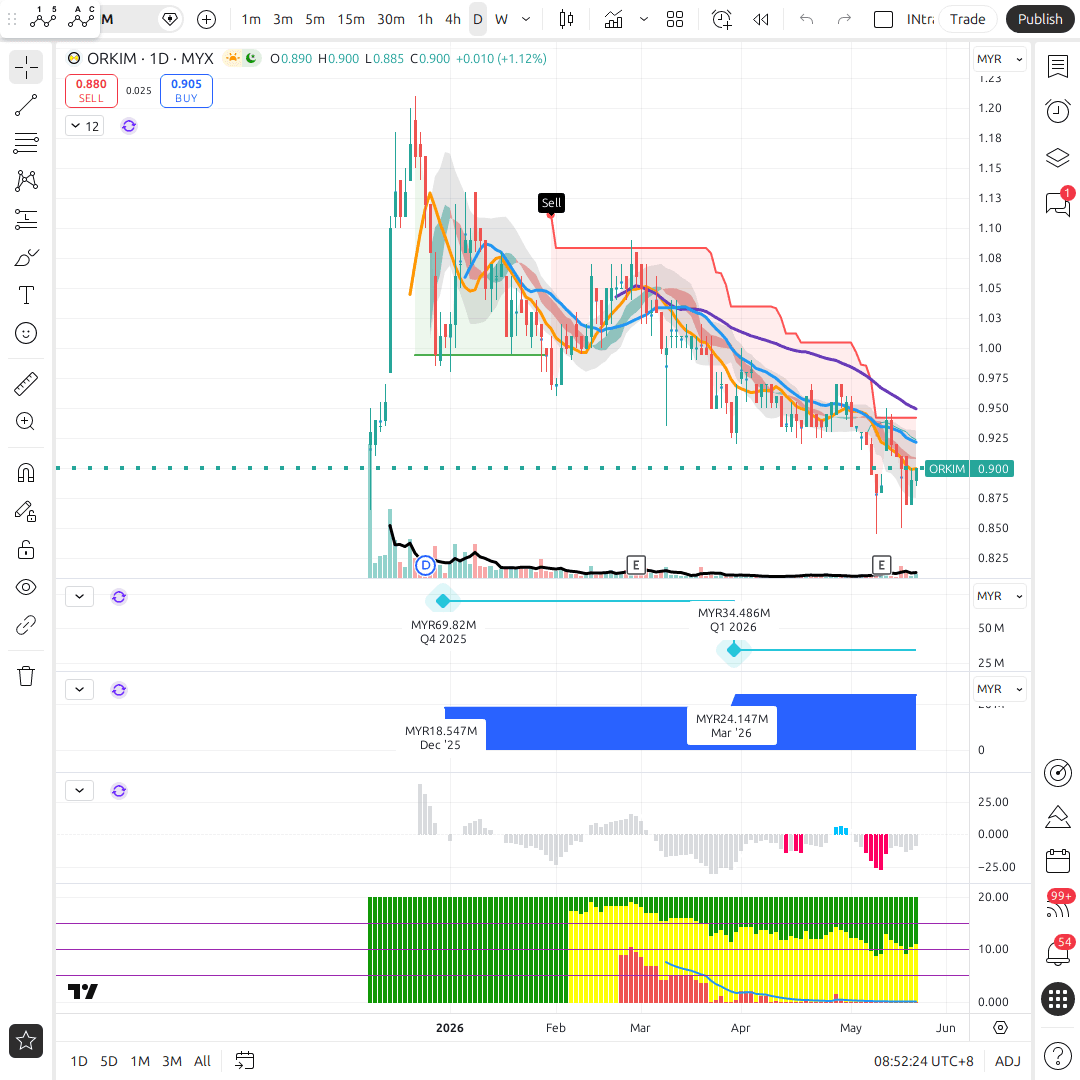
Company Profile: Orkim Berhad
Orkim Berhad: Malaysia's Dominant CPP Tanker Operator
Orkim Berhad (5348) is Malaysia's leading Clean Petroleum Products (CPP) and LPG tanker operator, commanding a 56% share of the domestic CPP tanker market. Listed on Bursa Malaysia on 9 December 2025 at an IPO price of RM0.92, the company's public debut marked a significant transition from private equity (Ekuinas) ownership to a publicly traded institution, now anchored by PNB as its dominant 60% shareholder.
With a fleet of 19 vessels following the delivery of MT Orkim Garnet in May 2026, Orkim plays an indispensable role in Malaysia's downstream energy supply chain — transporting refined petroleum products including petrol, diesel, aviation fuel, and LPG across the country's coastlines and ports.
Business Model: Stability Through Long-Term Contracts
Orkim's core competitive advantage lies in its contract structure: 95.2% of revenue is derived from long-term contracts, including Time Charters, Contract of Carriage (CVC), and Contract of Affreightment (COA). This contrasts with spot-market operators who face significant freight rate volatility. The long-term nature of these contracts creates a predictable, recurring revenue base that underpins earnings visibility.
Key customers include Malaysia's largest energy companies: PETRONAS, NGL, Petron, and BHPetrol. The top two customers account for 84% of total revenue.
Business Segments and Revenue Breakdown
| Segment | Q1 2026 Revenue | % of Revenue | Description |
|---|---|---|---|
| CPP (Clean Petroleum Products) | RM81.84M | 93% | Transport of petrol, diesel, aviation fuel, etc. |
| LPG (Liquefied Petroleum Gas) | RM6.19M | 7% | Transport of liquefied petroleum gas |
| Total | RM88.03M | 100% |
Fleet Expansion: A Growing Footprint
Orkim now operates a fleet of 19 vessels, comprising 16 CPP tankers, 2 LPG carriers, and 1 new Medium Range (MR) tanker. Two additional vessels are currently under construction:
- MT Orkim Jade — expected delivery end-2026 (USD23.57M each)
- MT Orkim Ruby — expected delivery early-2027
These additions will further cement Orkim's market leadership and expand its revenue-generating capacity.
Cabotage Policy: A Natural Economic Moat
Malaysia's Cabotage Policy restricts foreign-flagged vessels from operating domestic routes, effectively barring foreign competitors from entering Orkim's core market. This regulatory protection provides a durable competitive moat, supporting stable pricing power and limiting competitive pressure from lower-cost international operators.
Shariah Compliant Status
✅ Orkim Berhad is a Shariah-compliant stock, certified by the Shariah Advisory Council of the Securities Commission Malaysia. Muslim investors can participate in this investment without Shariah compliance concerns.
IPO Context: From PE-Owned to Public Company
Previously owned by Ekuinas (a government-linked private equity firm), which fully divested via the IPO, Orkim's ownership has now transitioned to PNB (Permodalan Nasional Berhad) as the 60% majority shareholder. PNB is one of Malaysia's largest institutional investors, bringing long-term stewardship orientation and strong governance credentials to the company's post-IPO phase.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
ORKIM keeps growing as fleet capacity expands. Q2 FY2026 revenue was RM87.34m with net profit of RM22.91m (26.2% net margin). For 1H26, net profit was RM47m (up 6.8% YoY) and revenue RM175.4m (up 14.9% YoY), with fleet utilisation of 91%.
| Quarter | Revenue (RM m) | Net Profit (RM m) | Net Margin |
|---|---|---|---|
| Q2 FY2026 (Jun 2026) | 87.34 | 22.91 | 26.2% |
| Q1 FY2026 (Mar 2026) | 88.03 | 24.11 | 27.4% |
| Q4 FY2025 (Dec 2025) | 84.31 | 19.31 | 22.9% |
| Q3 FY2025 (Sep 2025) | 72.93 | 13.30 | 18.2% |
The clean petroleum products (CPP) segment contributes about 94.3% of revenue, with the rest from LPG shipping. Q2 revenue slipped 0.8% QoQ and net profit fell 5.0% QoQ, but both remain well above Q3 FY2025.
Note: 1H25 figures are not fully in our database because ORKIM only listed in December 2025. The YoY comparisons above come from company-reported figures as covered by the media.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends
ORKIM targets a payout ratio of 50% to 70% of profit after tax attributable to shareholders each financial year, subject to cash flow, capex and working capital needs. It is not a binding commitment.
Our database records no dividend in Q2 FY2026. Public market data suggests the latest annual dividend was around 2 sen per share with an ex-date of 8 July 2026; we could not confirm this from an official announcement, so treat it as indicative only. At 77 sen, 2 sen is a yield of about 2.6%.
RHB cites dividend visibility as part of its Buy thesis. Note this is policy-based, not a guarantee.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation: Cheap or Expensive?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags: Risks You Need to Know
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessInvestment Scorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts & Future Risks
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion: Opportunity or Trap?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Transportation sector