McKesson Corporation (MCK)
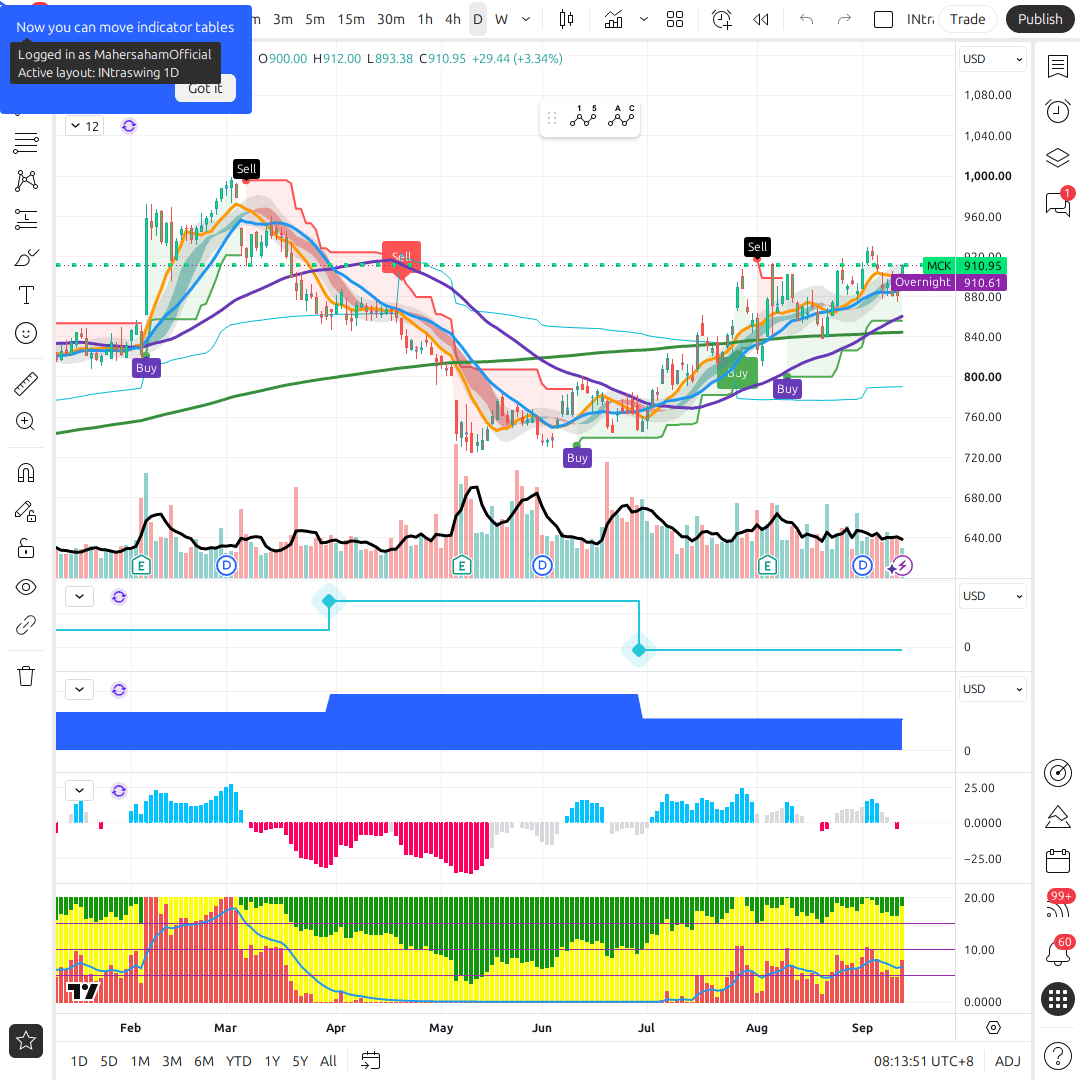
MCK Chart
1D • NYSE
15 Sept, 12:13 am
179.5 KB
Company Profile
Not Just a ‘Drug Wholesaler’ — McKesson Is Reinventing Itself
If you know McKesson (MCK) as a company that simply moves pharmaceuticals from manufacturers to pharmacies and hospitals on razor-thin margins, that story is out of date. Since 2025, McKesson has been executing a major strategic pivot: from a high-volume, low-margin pure pharmaceutical distributor into a more diversified, higher-margin specialty healthcare platform centered on Oncology & Multispecialty — while simultaneously shedding its slowest-growth segment via a corporate spin-off.
Revenue by Segment (FY2026)
| Segment | FY2026 Revenue | % of Total |
|---|---|---|
| North American Pharmaceutical | $336.65B | 83.45% |
| Oncology & Multispecialty | $48.42B | 12.00% |
| Medical-Surgical Solutions (being spun off) | $11.51B | 2.85% |
| Prescription Technology Solutions (RxTS) | $5.81B | 1.44% |
North American Pharmaceutical remains the revenue engine — but it is also, by a wide margin, the thinnest-margin segment in the portfolio. Oncology & Multispecialty is far smaller in absolute revenue, but it is the piece being aggressively built out through M&A because its margin profile and growth rate are structurally more attractive.
Building Out Oncology Through M&A
In just two months (April–June 2025), McKesson closed two large deals within the Oncology & Multispecialty segment:
- PRISM Vision Holdings — an 80% controlling stake for $875 million cash (April 2025), focused on ophthalmology/retina administrative services.
- Core Ventures (with Florida Cancer Specialists & Research Institute, FCS) — a 70% controlling stake for $2.5 billion cash (June 2025), a community oncology revitalization platform.
Notice the pattern across both deals: McKesson is buying majority stakes, not 100%. The original physician groups retain minority ownership (20% for PRISM Vision, 30% for FCS). This is a deliberate alignment structure — the specialist physicians actually running day-to-day operations keep economic skin in the game, lowering the risk they walk away and rebuild elsewhere post-acquisition.
Medical-Surgical Solutions Spin-off (‘NewCo’)
Announced in May 2025, McKesson plans to separate its Medical-Surgical Solutions segment (non-pharmaceutical medical/surgical supplies) into a standalone public company, currently referred to as ‘NewCo’. The original 12–18 month timeline (implying mid-2026) has slipped to the second half of calendar 2027 — a point worth flagging (see Catalysts/Risks section). In April 2026, Apollo Global Management invested $1.25 billion for a 13% minority stake in NewCo via convertible preferred equity, lending institutional credibility and part-funding the separation process.
Shariah Compliance Status
✅ Per Zoya’s screening, McKesson Corporation (MCK) is confirmed SHARIAH-COMPLIANT. This means its core business model — pharmaceutical distribution, oncology services, and health technology — passes the standard Shariah financial-ratio and business-activity screens Zoya applies.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Healthcare - Pharmaceutical Distribution & Services sector