Southwest Airlines (LUV)
LUV Chart
1D • NYSE
6 May, 02:00 am
195.5 KB
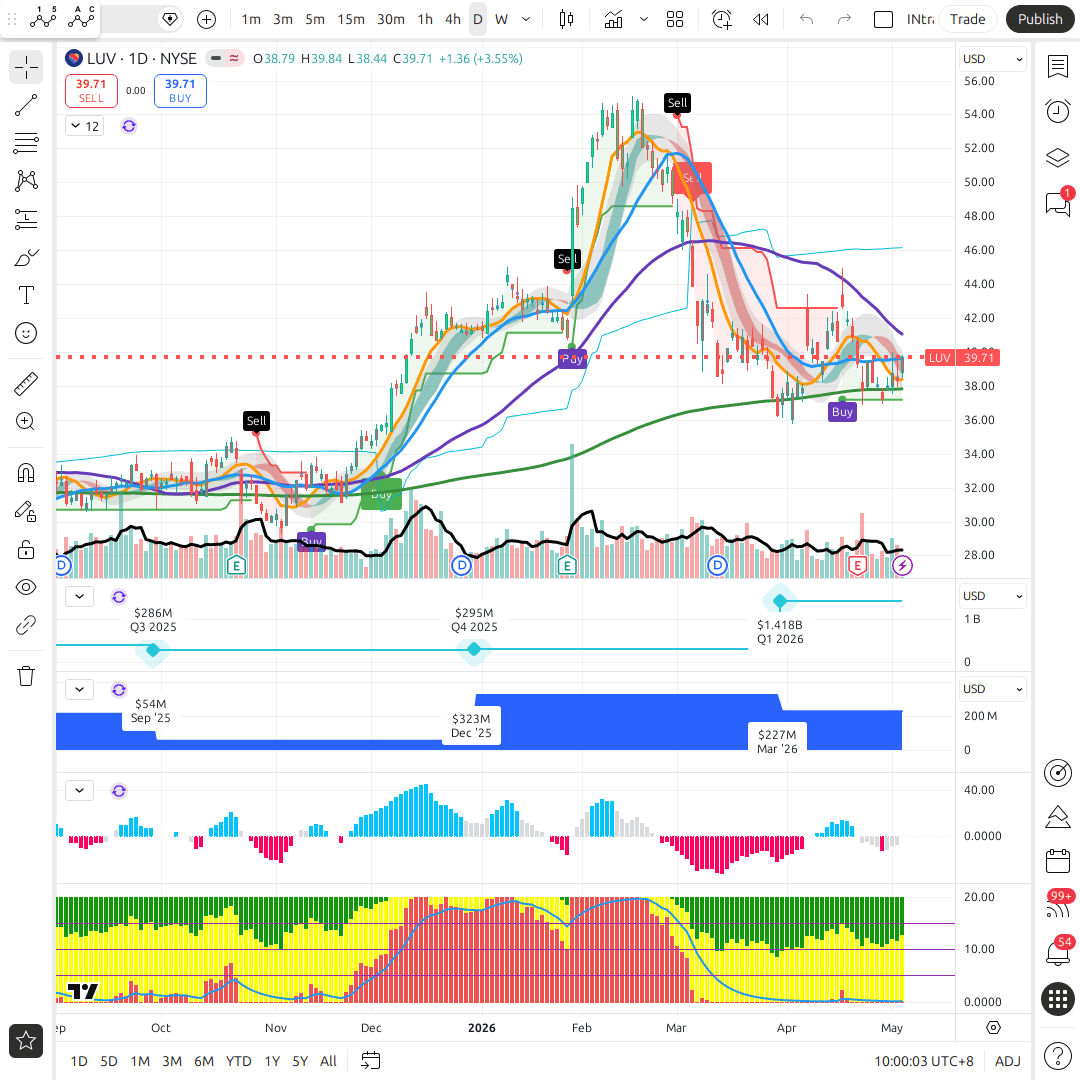
Company Profile
Southwest Airlines (LUV) is no longer the ‘budget airline with free bags’ you may remember. Since 2024, the company has been forced by activist investor Elliott Investment Management to overhaul its business model from the ground up — and that overhaul is now fully live. This is a forced-transformation story that appears to be working on the numbers, but where management itself is still visibly cautious about the road ahead. Understanding that tension is the key to reading everything else in this report.
What Southwest actually does today (post-transformation)
Through 2025, Southwest dismantled the ‘Bags Fly Free’ and open-seating identity that defined it since its founding over 50 years ago. The business model is now considerably more hybrid — closer to a legacy full-service carrier like Delta or United than a pure low-cost carrier:
- Assigned + premium (extra-legroom) seating — fully live as of 27 January 2026
- Checked bag fees — for the first time in company history
- A new Basic Economy fare tier
- GDS distribution via Expedia and Priceline — previously Southwest sold tickets almost exclusively through its own channels
- 6 new interline partnerships, and a revised Rapid Rewards loyalty structure
The Elliott story: why this happened
In 2024, Elliott Investment Management took a $1.9 billion stake in Southwest and launched an aggressive campaign — arguing that the open-seating and free-bags model was a direct cause of weak financial performance, and demanding removal of the then-CEO and Chairman. After a tense standoff, both sides reached a settlement in October 2024: the board was expanded to 13 members, with 5 Elliott nominees seated. This was not a voluntary pivot — it was change driven directly by activist shareholder pressure.
Revenue drivers
Southwest's revenue comes from three main streams: passenger (the large majority), cargo, and other revenue (including bag fees and new ancillary products). One standout from Q2 2026: managed/corporate business revenue (sales to companies rather than individual leisure travelers) grew +30% year-over-year to a record — an early sign that the distribution overhaul (GDS, corporate travel agencies) is starting to pay off.
Management
CEO Bob Jordan is a 38-year Southwest veteran who has held 15 different roles across the company, including Chief Commercial Officer, before becoming CEO. Following Elliott pressure, Southwest also split the Chairman role from the CEO role — Rakesh Gangwal was appointed Independent Chair effective 1 November 2024, a meaningful governance improvement.
⚠️ Shariah Status: NOT SHARIAH-COMPLIANT
Southwest Airlines is classified as NON_COMPLIANT. This stems from the company's reliance on interest-bearing conventional debt financing — leverage ratio of 2.2x and total debt of roughly $6,889 million — a standard feature of conventional airline financing (aircraft leases, working capital lines) but structurally incompatible with Shariah screening criteria. For Shariah-observant readers, LUV is not suitable as a core holding. This report is provided for educational purposes to help readers understand US equity market mechanics, not as investment advice.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison: LUV vs Legacy Majors & LCC Peers
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags: Risks Worth Weighing
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessInvestment Scorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts: Short, Medium & Long Term
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion: Genuine Turnaround, Or an Activist-Driven Re-Rating That's Already Played Out?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Airlines sector