Eli Lilly and Company (LLY)
LLY Chart
1D • NYSE
9 Oct, 09:13 am
191.1 KB
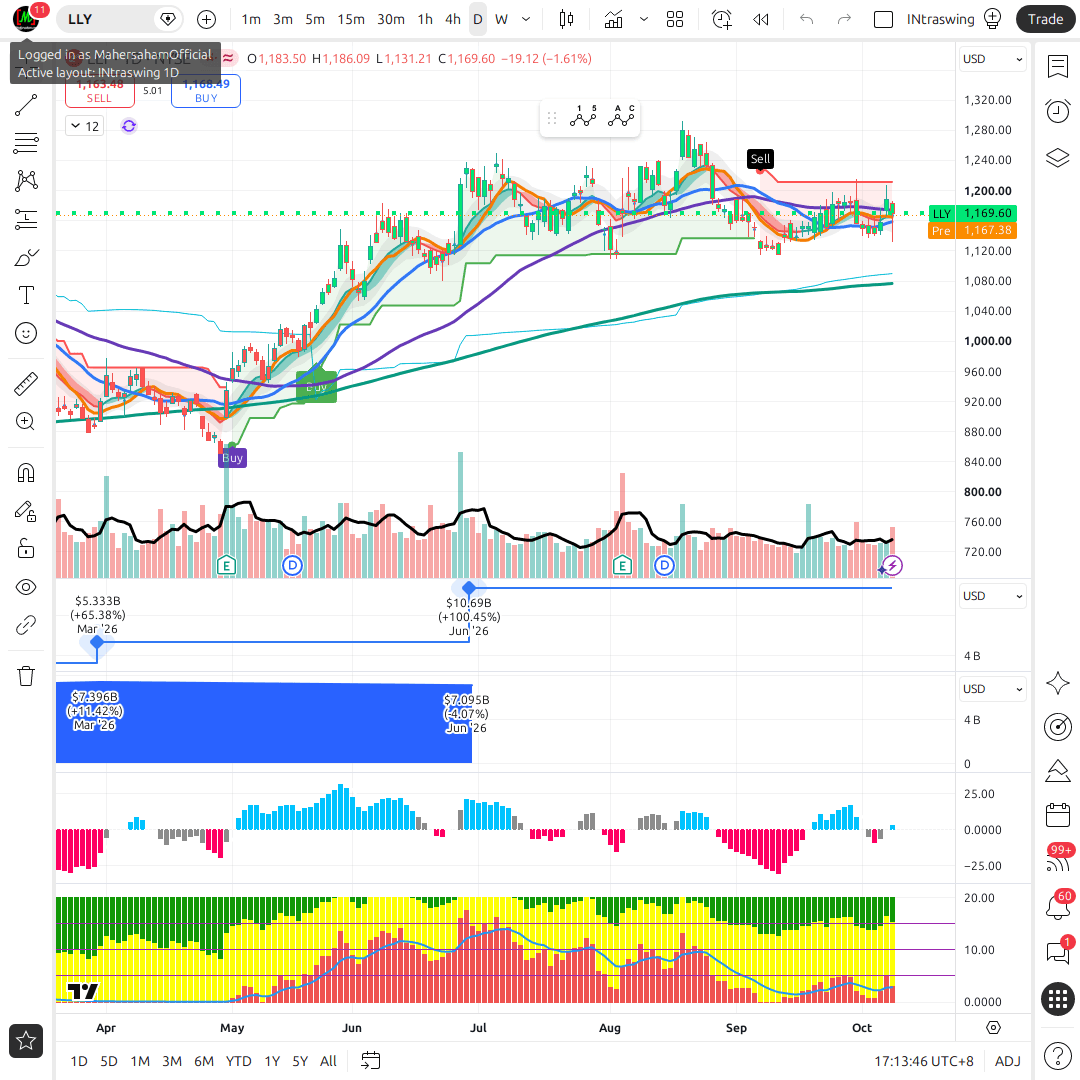
Company Profile: Eli Lilly and Company (LLY)
Eli Lilly used to be a stable but unglamorous diversified pharmaceutical company - diabetes, oncology, immunology, neuroscience, all running side by side with no single franchise dominating the story. That has completely changed since 2023-2026. Today, Lilly is the most valuable pharmaceutical company in the world (market cap ~$1.11 trillion, the 15th most valuable company globally), driven almost entirely by ONE franchise: GLP-1/incretin drugs for diabetes and obesity.
The single most important story here: Lilly has overtaken Novo Nordisk as the global GLP-1 market leader in 2026 - now holding roughly 60.1% combined obesity+diabetes GLP-1 market share versus Novo's 39.4%. Novo, meanwhile, is struggling - its own guidance projects 2026 sales to DECLINE 5-13% due to pricing pressure, patent losses and shrinking Medicaid obesity coverage. This is not a 'two similarly-sized rivals' story anymore - it is a clear market leadership handover to Lilly.
Q1 2026 Revenue Breakdown
Total company revenue: $19.8 billion (+56% YoY), driven by a 65% increase in volume, partially offset by a 13% decline in realized pricing (typical as a pharma company scales up and rebates/discounts grow).
- Mounjaro (diabetes): $8.66 billion worldwide - $4.2 billion US, $4.4 billion international (a huge jump versus $1.2 billion previously, largely driven by inclusion on China's NRDL reimbursement list)
- Zepbound (obesity): $4.16 billion in the US alone (+80% YoY)
- Mounjaro + Zepbound combined = ~$12.8 billion, roughly two-thirds of total company revenue
- US revenue up 43% to $12.1 billion; ex-US revenue grew even faster, up 81% to $7.7 billion - international markets are now the main growth engine
One thing worth watching: Trulicity, Lilly's older-generation diabetes drug that used to be its bread and butter, is now being cannibalized by Mounjaro itself as patients switch treatments. This is a normal part of the pharma product lifecycle - upgrading patients to newer, pricier drugs - but it means the 'legacy' segment will look flat or declining even as the overall company grows fast.
Management
David Ricks has served as Chair & CEO since 2017 - over 25 years with Lilly overall. He led the transformation from a diversified pharma company into a GLP-1 powerhouse and now oversees the next-generation pipeline (orforglipron, retatrutide).
Recent Corporate Actions
To address the manufacturing capacity constraints that have persisted since GLP-1 demand exploded (supply has long been a recurring operational risk for Lilly), the company issued $9.0 billion in notes in May 2026 across maturities ranging from 2028 to 2066 to fund new manufacturing capacity.
Shariah Compliance Status
✅ SHARIAH COMPLIANT (per Zoya US stock reference). As a large pharmaceutical company, the Shariah screen focuses on interest-bearing debt ratios relative to market cap and revenue sources - both criteria are monitored on an ongoing basis and Lilly currently remains compliant.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation Analysis: Eli Lilly (LLY)
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison (Big Pharma & GLP-1 Rivals)
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags & Risks - Read Before You Buy
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessLLY Scorecard - 8 Criteria
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts - What Could Move LLY's Price
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion - Priced for Perfection?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold Access