Fair Isaac Corporation (FICO)
FICO Chart
1D • NYSE
7 Oct, 08:52 am
169.0 KB
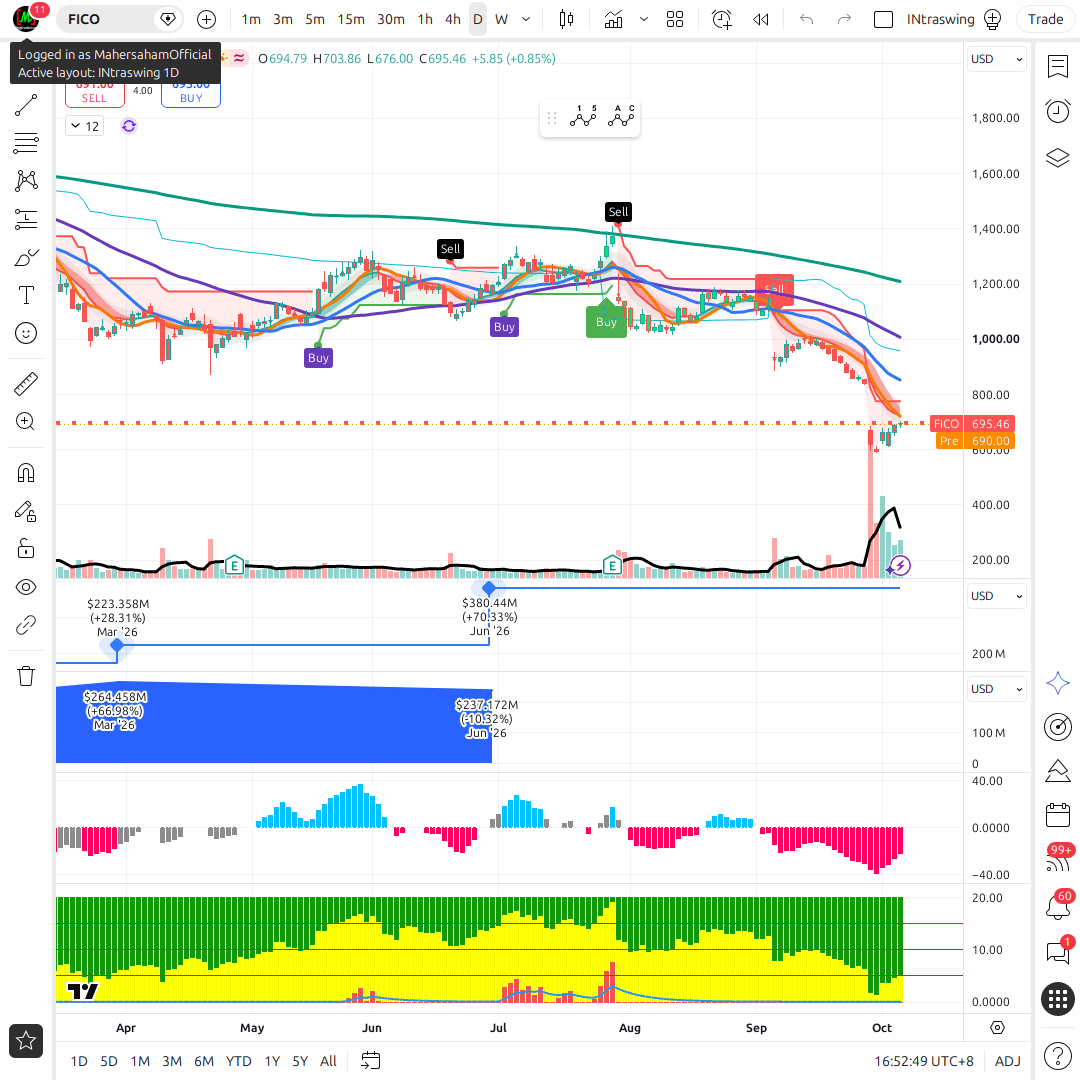
Company Profile: Fair Isaac Corporation (FICO)
Fair Isaac Corporation (NYSE: FICO) sits at a genuine inflection point, one rarely seen in the company's 30-plus year history. FICO is not just a ‘credit score company’ - it has run one of the most aggressive pricing-power strategies in software history, and that same strategy has just triggered the first real crack in a mortgage credit-scoring monopoly that has lasted more than three decades.
This is not a simple growth story, nor a simple value-trap story - it is a story of pricing power versus moat erosion. Understanding both sides of this tension is essential before drawing any conclusion.
What does FICO actually do?
FICO operates through two main segments:
- Scores segment - the famous ‘toll booth’ business: the FICO Score is used by nearly every US mortgage lender and credit card issuer to assess borrower credit risk. This segment splits into B2B (scores sold to banks/lenders for mortgage and loan origination) and B2C (scores sold directly to consumers through products like myFICO).
- Software segment - decision-management and analytics platforms (e.g. the FICO Platform, fraud detection, credit decisioning tools) sold on an Annual Recurring Revenue (ARR) basis to financial institutions globally. This behaves much more like a conventional SaaS business than the volume-dependent, mortgage-cycle-sensitive Scores segment.
Pricing power that exploded earnings
Since 2022, FICO has raised its wholesale per-score royalty for mortgage originations from as low as $0.60 to $10.00 in 2026 - a cumulative increase of over 1,600%, including a single 2026 hike from $4.95 to $10.00 (nearly doubling in one year). This directly drove Q2 FY2026 results (quarter ended March 31, 2026): Scores revenue jumped +60% YoY to $475.0M, driven by B2B scoring +72%, while B2C rose only 5%. Software revenue grew +7% to $216.7M with Software ARR +10%. Total Q2 FY26 revenue reached $692M versus $499M a year earlier.
The Scores segment (specifically B2B mortgage) is clearly the faster-growing segment relative to Software - but ironically, this fastest-growing segment is precisely the one now facing the most serious competitive threat in its history.
The first crack in a 30-year monopoly
FICO's aggressive pricing has alienated lenders, regulators and credit bureaus, opening the door for a rival. On April 23, 2026, Freddie Mac began accepting VantageScore (jointly developed by Equifax, Experian, and TransUnion) as an alternative to the FICO Score for mortgage underwriting; Fannie Mae followed shortly after under the FHFA's ‘lender choice’ framework. This ends FICO's decades-long de facto exclusivity in agency mortgage underwriting. VantageScore 4.0 is being offered at close to a 90% discount to FICO's bundled mortgage rate - an aggressive price war launched by the credit bureaus.
Despite this, FICO still commands a mid-to-high 90% market share in mortgage credit scoring, per BMO Capital Markets estimates - the moat is cracking at the edges, not yet broken, for now.
Shariah Compliance Status
Based on the Zoya reference database (zoya_us_stock_reference), FICO is classified as SHARIAH COMPLIANT. As a data and analytics software provider (rather than a conventional financial institution whose core business is lending/holding money with interest), FICO's business model generally aligns with shariah screening guidelines for the technology/data sector. That said, you should always verify current status on your preferred shariah screening platform, as classification can shift with the company's financial ratios over time.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation: FICO
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison: FICO vs Financial Data & Analytics Giants
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags: The Real Risks Behind FICO's Record Earnings
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFICO Scorecard: Strong Fundamentals vs Structural Risk
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts: What to Watch for FICO
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion: Fading Pricing Power, or a Temporary Fear-Driven Selloff?
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold Access