American International Group Inc (AIG)
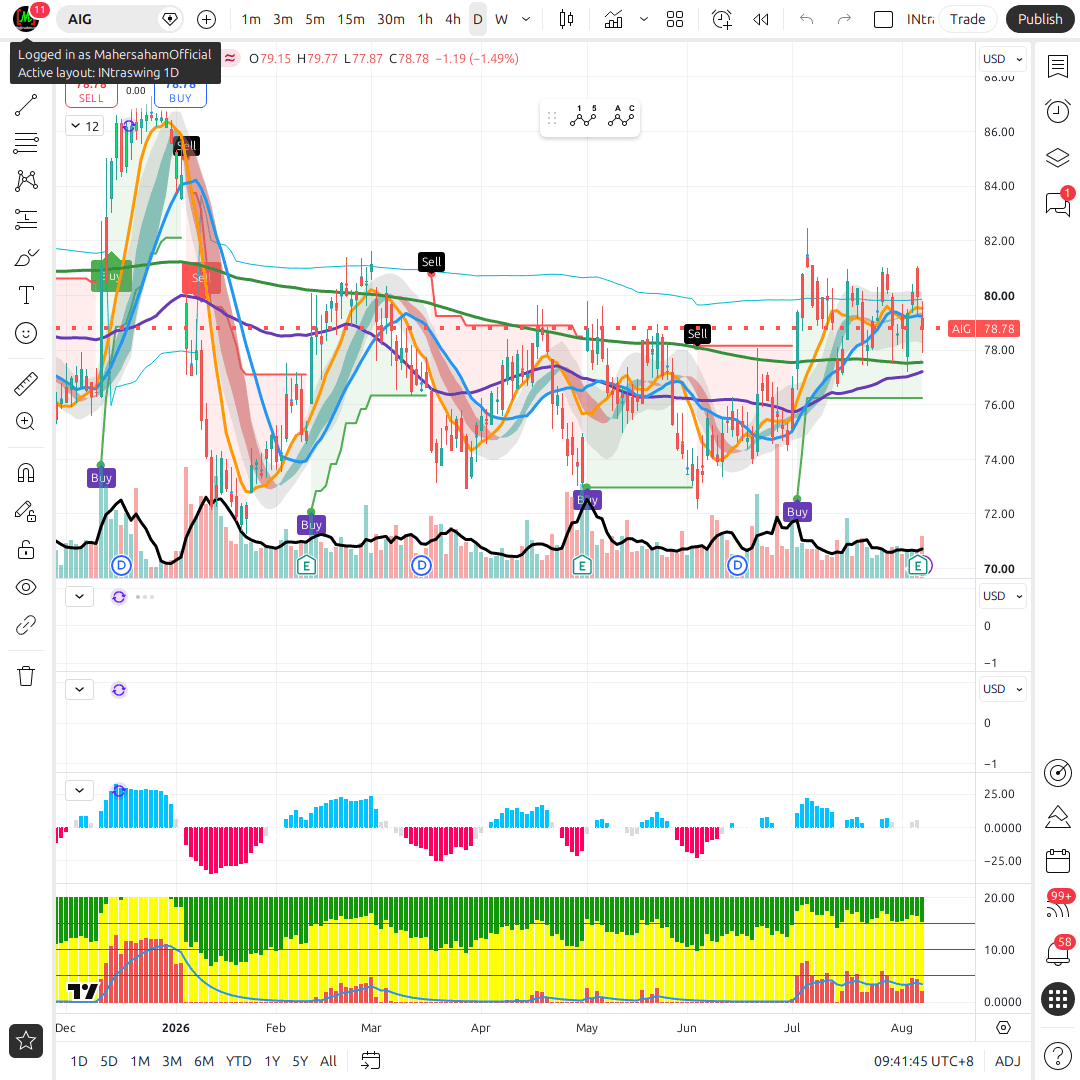
AIG Chart
1D • NYSE
8 Aug, 01:41 am
204.3 KB
Company Profile
From Insurance Conglomerate to Pure-Play P&C
If you still picture AIG as the sprawling insurance giant selling everything from life insurance to retirement annuities to property & casualty (P&C) coverage, it is time to update that mental model. In May 2026, AIG closed the sale of its remaining stake in Corebridge Financial (~25 million shares, ~$710 million net proceeds), completing a 5-year separation process that began with Corebridge's 2022 IPO and the 2024 sale of a majority stake to Nippon Life for $3.8 billion. Corebridge previously housed AIG's Life & Retirement business.
The result: AIG is now a pure-play General Insurance (P&C) company — no longer a diversified insurance conglomerate. This marks the culmination of the 'AIG 200' turnaround program driven by (former) Chairman & CEO Peter Zaffino over the past five years. If you come across older analysis describing AIG as a 'diversified life + P&C insurer,' that framing is stale — AIG's business structure has fundamentally changed.
Segment Structure: General Insurance
Following the Corebridge exit, AIG's sole core operating segment is General Insurance, split into three business lines:
| Business Line | NPW Growth (Q1 2026, reported) | Q1 2026 Underwriting Income |
|---|---|---|
| North America Commercial | +37% YoY | Largest contributor to combined ratio improvement |
| International Commercial | +21% YoY | $278 million (+16% YoY) |
| Global Personal | +17% YoY | $169 million (swing from a $126 million loss in Q1 2025) |
Overall net premiums written grew 24% YoY on a reported basis (18% on a constant-dollar basis) — broad-based growth across all three business lines, not a single segment skewing the average.
Shariah Compliance Status: NON-COMPLIANT ❌
AIG is classified as NON_COMPLIANT from a Shariah perspective. This matters before you read any other section of this report: AIG is a conventional (non-Takaful) insurer. Conventional insurance conflicts with Shariah principles for two core reasons — (1) riba, since a substantial share of AIG's investment income comes from interest-bearing bond and fixed-income portfolios ($712 million in net investment income in Q1 2026 alone), and (2) gharar (excessive uncertainty) inherent in conventional insurance contract structures, which lack the cooperative/tabarru'-based risk-sharing model used in Takaful. This report is provided for educational and comparative purposes only — it is not an investment recommendation for a Shariah-conscious audience.
Key Corporate Actions
- May 2026: Full exit from Corebridge Financial (~$710 million)
- 2024: Majority Corebridge stake sold to Nippon Life ($3.8 billion)
- Current buyback authorization: up to $10 billion
- Full-year 2025: ~$6.8 billion returned to shareholders (~$5.8 billion buybacks + ~$1.0 billion dividends), share count reduced 11%
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
This section is being refreshed with the latest figures. Please check back soon.
Dividends
This section is being refreshed with the latest figures. Please check back soon.
Valuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Financials sector