Skyworks Solutions, Inc. (SWKS)
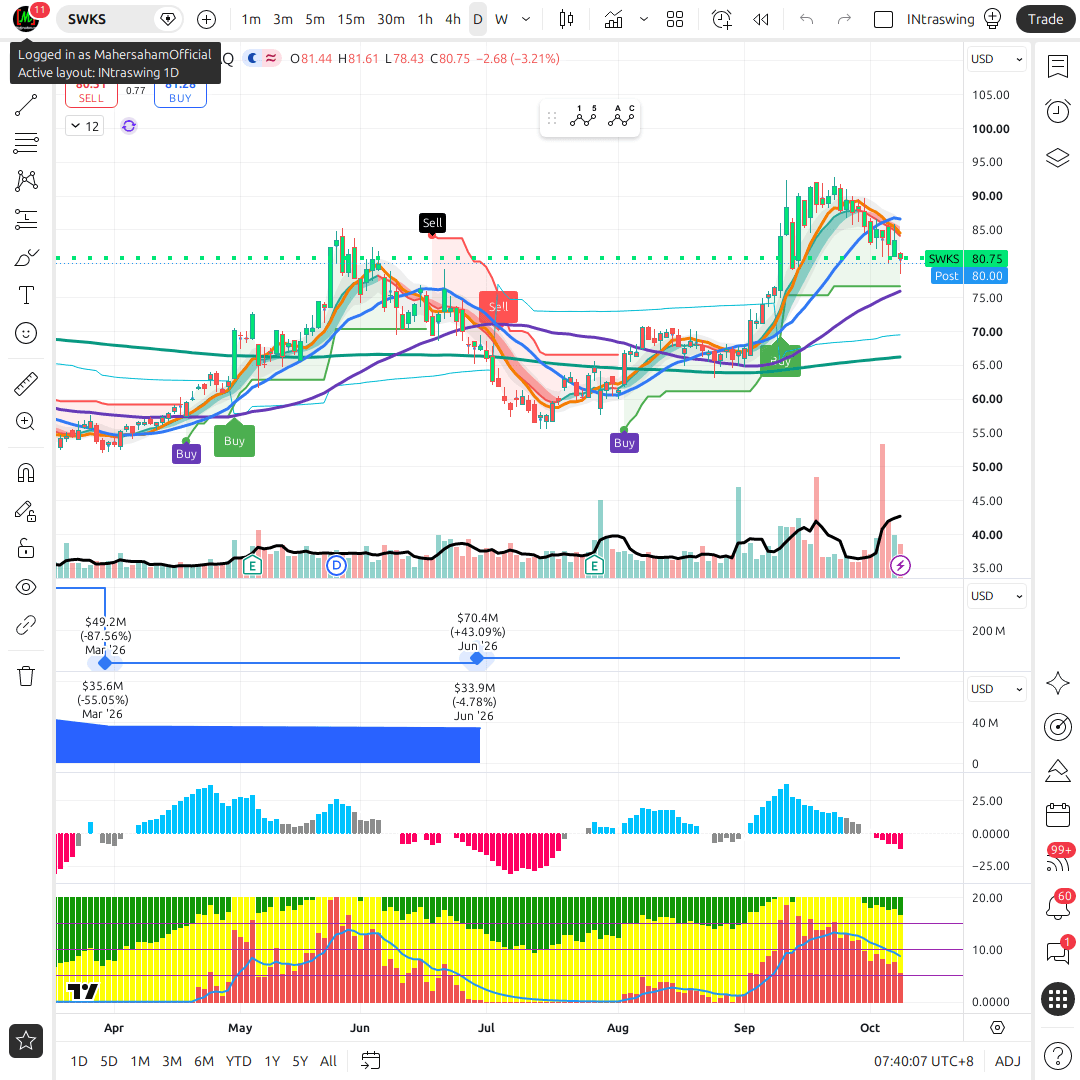
SWKS Chart
1D • NASDAQ
8 Oct, 11:40 pm
180.4 KB
Company Profile
A company mid-transformation, not just an RF chipmaker holding steady
Skyworks Solutions (NASDAQ: SWKS) makes the radio-frequency (RF) front-end chips — filters, amplifiers, switches and integrated modules — that let phones, routers, cars and industrial devices talk wirelessly. But describing Skyworks today purely as an RF-chip supplier misses the real story: the company is in the middle of the largest deal in its history, a proposed merger with fellow RF specialist Qorvo (QRVO).
📈 The Qorvo merger, in plain terms: announced October 27, 2025, this is a cash-and-stock deal worth roughly $22.0 billion in combined enterprise value. Qorvo shareholders would receive 0.960 Skyworks shares plus $32.50 in cash for every Qorvo share. On a pro forma basis, existing Skyworks holders would own about 63% of the combined company and Qorvo holders about 37%. Both companies' shareholders already voted to approve the deal on February 11, 2026. However, the U.S. Federal Trade Commission issued a Second Request for information on February 5, 2026 — meaning the deal is still under active antitrust review and has NOT closed. Management has talked about accelerating the close to end-2026 versus an original 'early 2027' target, but the actual timing now depends entirely on when (and on what terms) the FTC clears the transaction.
Why merge with Qorvo? Skyworks and Qorvo are the two largest pure-play RF front-end suppliers outside of the in-house RF capabilities at Broadcom and Qualcomm. Combining gives the merged company more scale, a broader customer base beyond mobile, and management is targeting roughly $500 million in annual cost synergies. It is a consolidation play for a maturing, competitive niche of the semiconductor industry.
Where the revenue actually comes from
In the most recently reported quarter (Q2 FY2026, ended around March 2026, reported May 5, 2026), Skyworks posted revenue of $944 million, ahead of its own guidance, with adjusted EPS of $1.15 versus $1.04 consensus. Revenue splits into two segments that are moving in very different directions:
- Mobile (58% of revenue): came in 'ahead of expectations,' largely on healthy sell-through at Skyworks' top customer, Apple. This segment is also the company's biggest single risk — see the concentration discussion below.
- Broad Markets (42% of revenue) — WiFi, data center, automotive, industrial infrastructure and IoT: up 10% year-on-year, marking nine consecutive quarters of growth and running at roughly $400 million per quarter. Three years ago this segment was under 25% of total revenue; today it is approaching half. This is the diversification-away-from-mobile story that bulls point to.
An earlier quarter, Q1 FY2026 (reported February 3, 2026), was also strong: revenue of $1.035 billion and non-GAAP EPS of $1.54, with $339 million of free cash flow generated and $106 million paid out in dividends.
Leadership
CEO Philip Brace took over on February 17, 2025, succeeding long-time CEO Liam Griffin. Brace's background spans semiconductors, servers, IoT and storage — he was previously President and CEO of Sierra Wireless and Executive Chairman of Inseego, and began his career in engineering and management roles at Intel and LSI Corporation. He holds a bachelor's degree in computer engineering from the University of Waterloo and a master's in electrical engineering from California State University, Sacramento, and currently also sits on BlackBerry's board.
Shariah compliance status
✅ Based on the Zoya screening methodology used at mahersaham.com, Skyworks Solutions is currently classified as Shariah COMPLIANT — relevant for Muslim investors who want RF/semiconductor exposure without straying from screening criteria. As always, compliance status can change over time as balance sheet and revenue composition shift (notably, watch this after the Qorvo merger financing raises debt levels — see the Financials section).
So what for the investor? Skyworks right now is best understood as a 'deal arbitrage plus fundamentals' story, not a simple steady-state valuation exercise. The Qorvo merger, if it closes on reasonable terms, could reshape the company's scale and diversification for years. If it stalls, gets restructured with divestitures, or is blocked, the story reverts to a standalone RF supplier still working through an Apple-concentration and earnings-trough problem.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
Skyworks posted revenue of $934.8M in Q3 FY2026 (quarter ended July 3, 2026), down 3.1% YoY but ahead of expectations. Mobile was about 57% of sales and Broad Markets 43% (about $402M, up 8% YoY, led by automotive and data center). The largest customer (Apple) is roughly 57% of revenue.
| Quarter | Revenue ($M) | GAAP EPS | Non-GAAP EPS |
|---|---|---|---|
| Q3 FY26 (Jul 2026) | 934.8 | 0.22 | 1.08 |
| Q2 FY26 (Apr 2026) | 943.7 | 0.24 | 1.15 |
| Q1 FY26 (Jan 2026) | 1,035.4 | 0.53 | 1.54 |
| Q3 FY25 | 965.0 | 0.70 | 1.33 |
| Q2 FY25 | 953.2 | 0.43 | 1.24 |
| Q1 FY25 | 1,068.5 | 1.00 | 1.60 |
Non-GAAP gross margin was 44.9% (47.1% a year ago). Q4 guidance: revenue of $1.01-1.06B, gross margin 44-45%, and non-GAAP EPS of about $1.27 at the midpoint. Rising input costs continue to pressure margins despite selective pricing actions.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends
Dividend suspended
On July 28, 2026, Skyworks' board decided not to declare further quarterly dividends given the pending merger. The last dividend was $0.71 per share (declared May 5, 2026). Forward dividend yield is now 0%.
In its place, the board authorised a share repurchase programme of up to $2.0B through January 31, 2029. This shifts the return profile from cash income to flexible capital return. Dividend-focused investors should reassess whether the stock still fits.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRelated Stocks
Other stocks in the Technology sector