PTC Inc. (PTC)
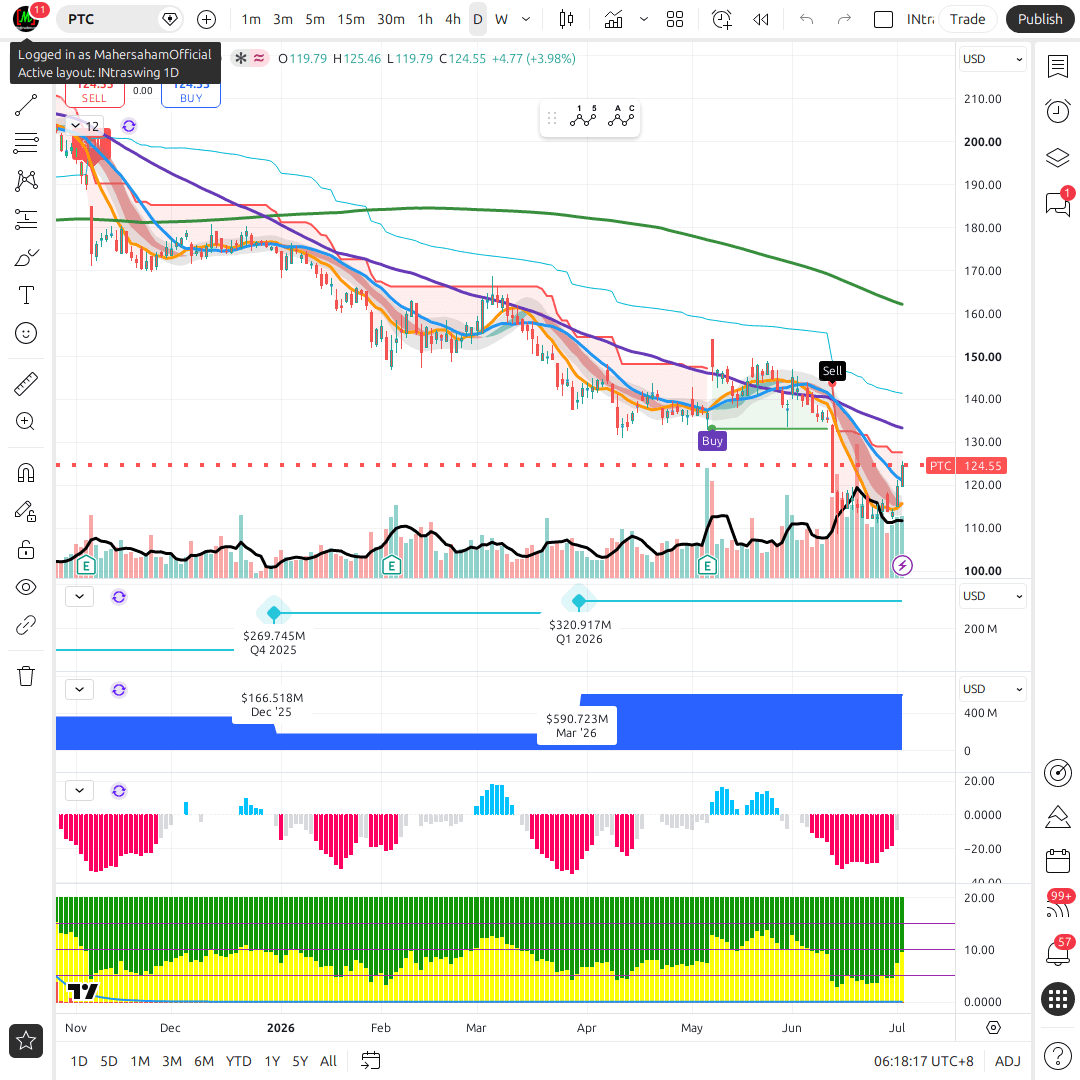
PTC Chart
1D • NASDAQ
3 Jul, 10:18 pm
178.0 KB
Company Profile
From a Diversified Company to a Pure-Play CAD/PLM Leader
PTC Inc. (NASDAQ: PTC) was founded in 1985 in Boston, Massachusetts, originally as Parametric Technology Corporation. For nearly four decades, PTC has built a reputation as one of the world's leading industrial engineering software companies, anchored by two core products: Creo (CAD - Computer-Aided Design software for engineering design and drafting) and Windchill (PLM - Product Lifecycle Management software for governing product data across its lifecycle).
PTC's story in 2026 isn't just about the numbers - it's a story of strategic transformation. On November 5, 2025, PTC announced the sale of two business units, Kepware (industrial connectivity) and ThingWorx (IoT platform), to private equity firm TPG. The deal was worth over $523 million in cash at close on March 16, 2026. In effect, PTC deliberately shed the IoT diversification wing that never scaled to the size of its core CAD/PLM business, to refocus purely on what it does best: CAD and PLM software for discrete manufacturers, automotive, and aerospace/defense customers.
Complementing this refocusing, PTC also acquired IncQuery Group on April 2, 2025 - an ALM (Application Lifecycle Management) and systems engineering consultancy that strengthens Windchill's systems-engineering stack. In short: PTC is no longer 'an IoT company that also does CAD' - it's returning to being a pure-play, high-margin CAD/PLM software leader, using the divestiture proceeds to fund aggressive buybacks ($626 million in Q2 FY2026 alone).
Segment Breakdown (Q2 FY2026)
| Segment | Revenue | YoY Growth |
|---|---|---|
| PLM (Windchill) | $492M | +24% |
| CAD (Creo) | $282M | +17% |
The PLM segment is now the primary growth engine, outpacing the more mature CAD segment - a sign that large customers (automotive, aerospace, defense) are increasingly relying on Windchill to manage more complex product data.
Leadership
Neil Barua has led PTC as CEO since February 2024. Worth noting transparently: he was a net seller of shares through 2025 (11 separate disposal transactions, roughly 106,780 shares worth approximately $6.8 million). This isn't necessarily alarming for an executive with large equity compensation, but it's worth watching alongside the stock's steep decline.
Shariah Compliance Status
PTC Inc. is confirmed SHARIAH COMPLIANT per Zoya screening, making it a considerable option for investors prioritizing Shariah-compliant investments within the US industrial software sector.
So what does this mean for investors? PTC is in a 'back to basics' phase - shedding businesses that never achieved meaningful scale, focusing on high-margin, recurring-revenue (ARR) business, while using divestiture proceeds to return value to shareholders via share buybacks. The question is whether the market will recognize this refocusing, or continue to be overshadowed by short-term issues unrelated to the underlying business fundamentals.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
PTC is a high-margin software company that converts a lot of its revenue into cash. In fiscal Q3 2026 it generated $249M of free cash flow (FCF) on $600.0M of revenue, a FCF margin of about 41%. FCF rose 3% YoY and operating cash flow was $261M.
| Metric | Q3 FY2026 | Note |
|---|---|---|
| Revenue | $600.0M | Down 7% (down 8% constant currency), divestitures |
| ARR (constant currency) | $2,448M | Up 9.1% ex-divested |
| Non-GAAP operating margin | 41.4% | Down 290 bps |
| GAAP operating margin | 27.7% | Down 480 bps |
| Free cash flow | $249M | Up 3% YoY |
| Stock-based compensation | $59.4M | About 10% of revenue |
| Cash | $351.5M | vs $184.4M at 30 Sep 2025 |
| Total debt | $1,423.3M | vs $1,197.4M at 30 Sep 2025 |
Debt went up because PTC borrowed to fund large buybacks, more than $1.6B in FY26. Net debt is roughly $1.07B (our calculation), which is under 1.3x FY26 FCF guidance of about $850M. That is a comfortable balance sheet for a software business.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividends
PTC does not pay a dividend. The company returns cash through share buybacks instead, and in FY2026 it repurchased more than $1.6B of stock, well above its target.
For income investors, nothing changes: there is no yield to collect now, and under the Schneider agreement shareholders receive $205 in cash at closing rather than ongoing payouts.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold Access