Cintas Corporation (CTAS)
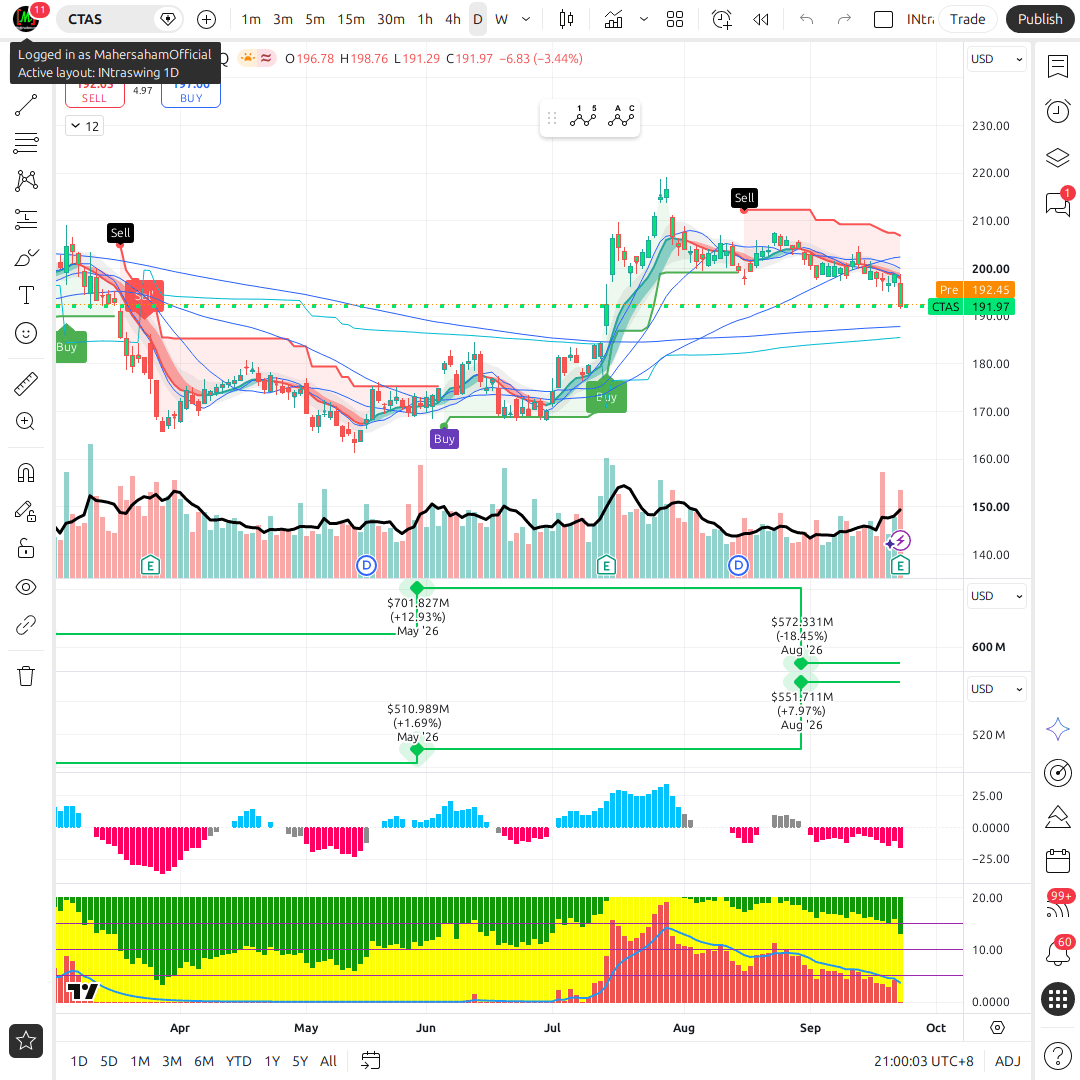
CTAS Chart
1D • NASDAQ
24 Sept, 01:00 pm
180.5 KB
Company Profile: Cintas Corporation (CTAS)
Cintas Corporation (NASDAQ: CTAS) is the largest player in the uniform rental and facility services industry in North America, with a market cap of roughly $81.8 billion. But the big story right now isn't just "the uniform company" narrative — Cintas is in the process of acquiring UniFirst Corporation, its #2/#3 competitor in the same industry, in a deal worth $5.5 billion in enterprise value.
The Headline Story: The UniFirst Acquisition
Announced in March 2026, Cintas will acquire UniFirst through a cash-and-stock structure. UniFirst shareholders have already approved the deal. This is not a routine bolt-on acquisition — it's an industry consolidation event where the dominant player (Cintas) absorbs one of its main rivals. If it closes successfully, the competitive landscape of the uniform/workwear rental industry changes meaningfully.
Current status: the deal is under a deeper FTC antitrust review ("Second Request") — a real, substantive review rather than a formality. The deal is expected to close in the second half of calendar 2026.
Business Segment Breakdown (FY2025)
| Segment | % of Revenue | Description |
|---|---|---|
| Uniform Rental & Facility Services | ~77% | Core business — uniform/garment rental, flame-resistant clothing, mats/mops/shop towels, restroom supplies, route-based catalog sales |
| First Aid & Safety Services | ~12% | First aid and safety products, workplace water services |
| All Other (Fire Protection + Direct Sales) | ~11% | Fire protection services and direct uniform sales |
Cintas's business model is built around recurring, route-based revenue — customers (mostly businesses, factories, hospitals) subscribe to regular (weekly/bi-weekly) services for uniforms, mats, and safety supplies. This produces stable, predictable revenue compared to one-off product sales.
Shariah Compliance Status
Per Zoya's reference data (zoya_us_stock_reference), CTAS is flagged as COMPLIANT. The core business (uniform rental, safety services) is not interest-based revenue. That said, worth noting: once the UniFirst deal closes, the company's debt levels will step up to fund part of the $5.5 billion transaction. That means debt-to-asset/market-cap ratios are worth re-checking after the deal closes — not a compliance concern today, but a forward-looking watch item.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCANSLIM Analysis
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessFinancial Analysis
Fiscal Q1 2027 (ended August 31, 2026) was the first quarter in Cintas history with revenue above $3 billion. The key numbers:
| Metric | Q1 FY2027 | Note |
|---|---|---|
| Revenue | $3.01 billion | +10.9% YoY |
| Organic growth | 8.9% | Excludes acquisitions, currency and workday differences |
| Uniform Rental and Facility Services | 8.0% organic | Segment gross margin a record 50.8% (+110 bps) |
| First Aid and Safety | 14.2% organic | Fastest-growing segment |
| Gross margin | 51.5% | All-time high |
| Operating income | $711.9 million | +15.2% YoY, 23.6% margin |
| Net income | $551.7 million | +12.3% from $491.1 million |
| Adjusted EPS | $1.39 | +15.8% YoY |
| Free cash flow | $464.8 million | vs $312.5 million a year ago |
Organic growth accelerating to 8.9% (from 8.4% for all of FY2026) is notable because management framed it as volume-driven rather than price-driven. The 23.6% operating margin shows operating leverage still at work, and free cash flow rising to $464.8 million leaves room to fund dividends and buybacks at once.
FY2027 guidance was raised: revenue of $12.15-$12.27 billion (+7.9% to +8.9%) and adjusted EPS of $5.45-$5.54. The outlook assumes one extra workday versus FY2026, worth roughly 40-50 bps of revenue growth.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessDividend Analysis
Cintas raised its quarterly dividend 15.6% to $0.52 per share, or $2.08 annualized, extending a streak of 43 consecutive years of annual increases. At about $192, the yield is roughly 1.1%.
| Metric | Value |
|---|---|
| New quarterly dividend | $0.52 |
| Annualized dividend | $2.08 |
| Dividend increase | +15.6% |
| Yield (price ~$192) | ~1.1% |
| Payout ratio (on FY2027 guided EPS midpoint) | ~38% |
| Consecutive annual increases | 43 years |
A 1.1% yield is low for anyone seeking immediate income. But the 15.6% raise outpaced guided EPS growth (10-12%), and the payout ratio remains below 40%. The dividend is best viewed as a bonus from a business that compounds capital rather than the main reason to own the stock.
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessValuation: Cintas Corporation (CTAS)
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessPeer Comparison
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessRed Flags
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessScorecard
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessCatalysts
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold AccessConclusion
Exclusive Gold Members Content
Get in-depth analysis, target prices, and investment recommendations with Gold Members subscription.
How to Get Gold Access